Railroads Of Today: Class I Map, PSR & the 2026 Industry
Last revised: September 14, 2026
By: Adam Burns
U.S. freight rail in 2026 is six Class I names on a plant of nearly 140,000 miles, plus about 615 short lines and regionals that own the rest. The national network stood at 164,822 miles in 1980 and 136,650 in 2020. Class I railroads still run about two-thirds of those miles, 87 percent of the people, and 94 percent of the revenue. They move on the order of 1.5 billion tons a year and about 40 percent of long-distance ton-miles. Precision Scheduled Railroading is how they run. The Surface Transportation Board is the regulator. Union Pacific’s proposed purchase of Norfolk Southern is still before that Board. The 2020s dates—Canadian Pacific Kansas City, East Palestine, the application itself—are that decade. This page is the industry as it stands.
What follows here is the 2026 map, the operating gospel, the Board, the traffic mix, and the hundreds of smaller railroads that still pick up and set out on the miles the Class Is sold.
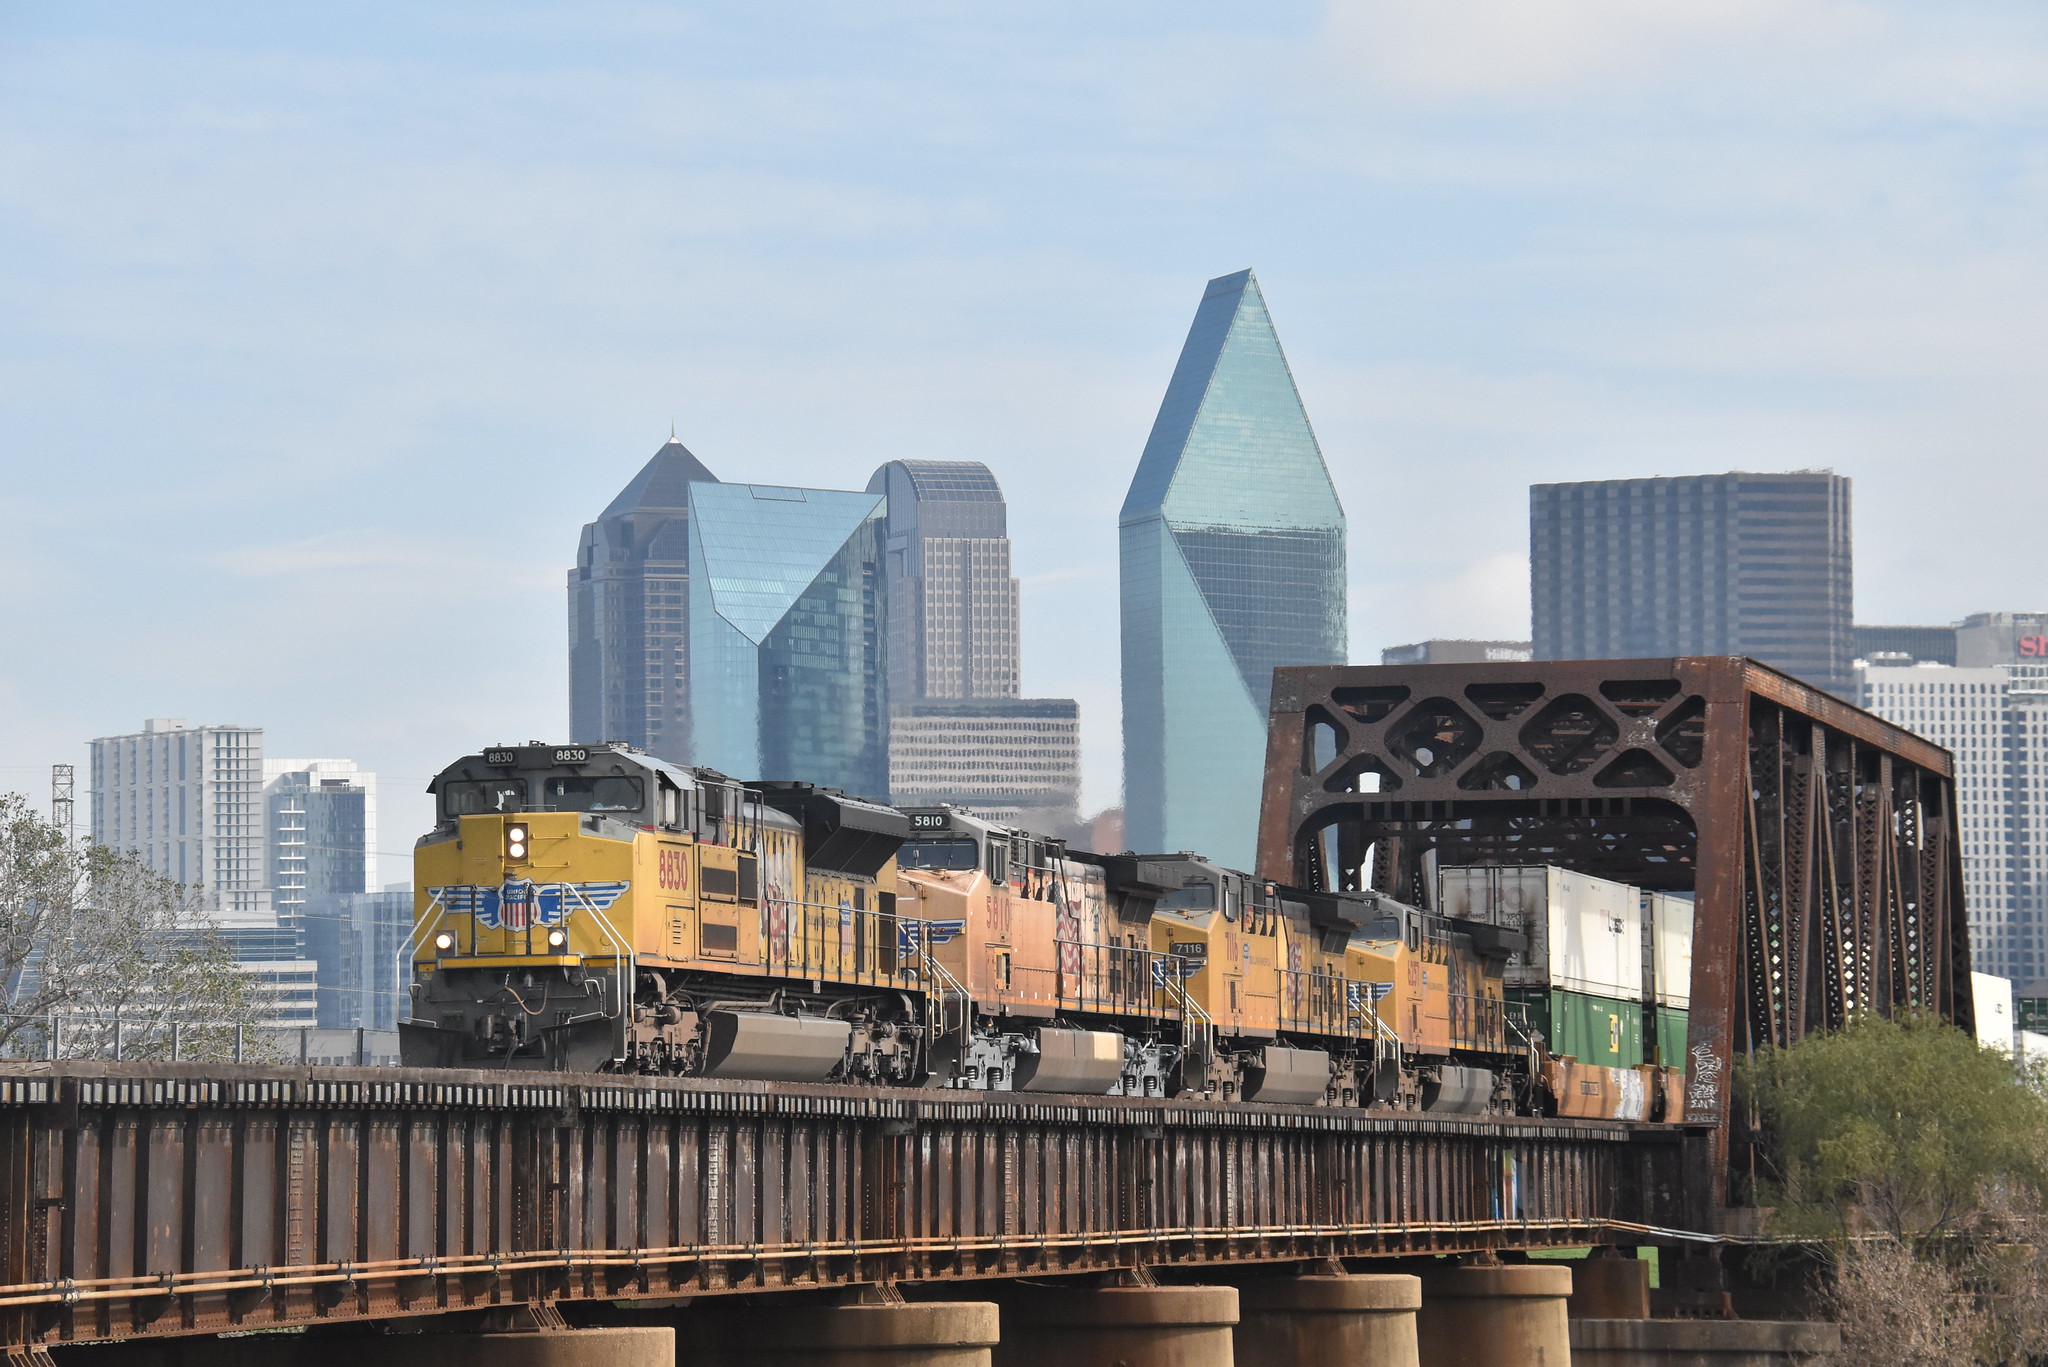
Union Pacific SD70ACe 8830 leads several GEs westbound across the Trinity River bridge with downtown Dallas, Texas, in the background on November 18, 2023. Doug Kroll photo.
On this page: At a glance · The 2026 map · How they run · The Surface Transportation Board · What they haul · Short lines and regionals · Passenger on freight rails · The case still open
At a glance
| Item | Detail |
|---|---|
| National freight network | 164,822 miles (1980) / 136,650 miles (2020). AAR current talking number: nearly 140,000. Not the Class I miles-of-road series on the decade leaves (91,773 in 2020) |
| Class I freights, 2026 | Six: BNSF, Union Pacific, CSX, Norfolk Southern, Canadian National, CPKC. List and thresholds on Class I |
| Class II and III | About 615 short lines and regionals |
| Class I share of the industry | About 67% of mileage, 87% of employees, 94% of freight revenue |
| Direct rail employment | About 153,000. Pay and careers on railroad jobs |
| Class I pay and benefits | About $135,000 to almost $190,000 a year for a craft package |
| Private reinvestment, 1980–2024 | About $840 billion of railroad money, capital plus maintenance |
| Average rail rates | Inflation-adjusted revenue per ton-mile 44% lower in 2024 than in 1981 |
| Freight moved | On the order of 1.5 billion tons in a typical year. About 40% of U.S. long-distance ton-miles |
| Intermodal | About 25% of major-railroad revenue (2023). Largest single traffic segment |
| Places in the Official Guide | About 75,500 (1916) / 53,000 (1957) / 34,000 (2004) |
| UP–NS | Announced 2025. Still before the Board as of September 2026. Docket dates on the 2020s |
| Not this page | 2020s dates (CPKC combination day, East Palestine, Floridian, Pan Am). Staggers as a statute. Diesel types. Company encyclopedias |
National-network miles 164,822 / 136,650 and the current AAR snapshot from Association of American Railroads, Freight Rail Facts & Figures, and Railroad Facts. Information compiled September 14, 2026.
The 2026 map
Six Class I freight railroads hold the long-haul map. BNSF and Union Pacific split the West. CSX and Norfolk Southern split the East. Canadian National runs a mid-continent U.S. franchise on former Illinois Central, Wisconsin Central, and Grand Trunk iron. Canadian Pacific Kansas City is the north–south railroad, Canada to Mexico on one company. Kansas City Southern is no longer a separate Class I. How CPKC was assembled is the 2020s. What it is, in 2026, is the sixth name on this list.
Chicago is still the hub. All six Class Is operate there. About one freight carload or intermodal unit in four originates, terminates, or passes through that district. The Mississippi remains a rough dividing line for the two U.S. duopolies; the Canadians cross it on purpose. A single-company Atlantic–Pacific freight railroad does not exist. Union Pacific and Norfolk Southern have asked the Board to create one. Until the Board rules, the map is six.
The definition and the dollar threshold that makes a railroad Class I—about $1.095 billion in annual operating revenue for 2025, inflation-adjusted by the Board—are Class I railroads. Berkshire Hathaway still owns BNSF. The other five report to public shareholders. Company pages carry the corporate histories.
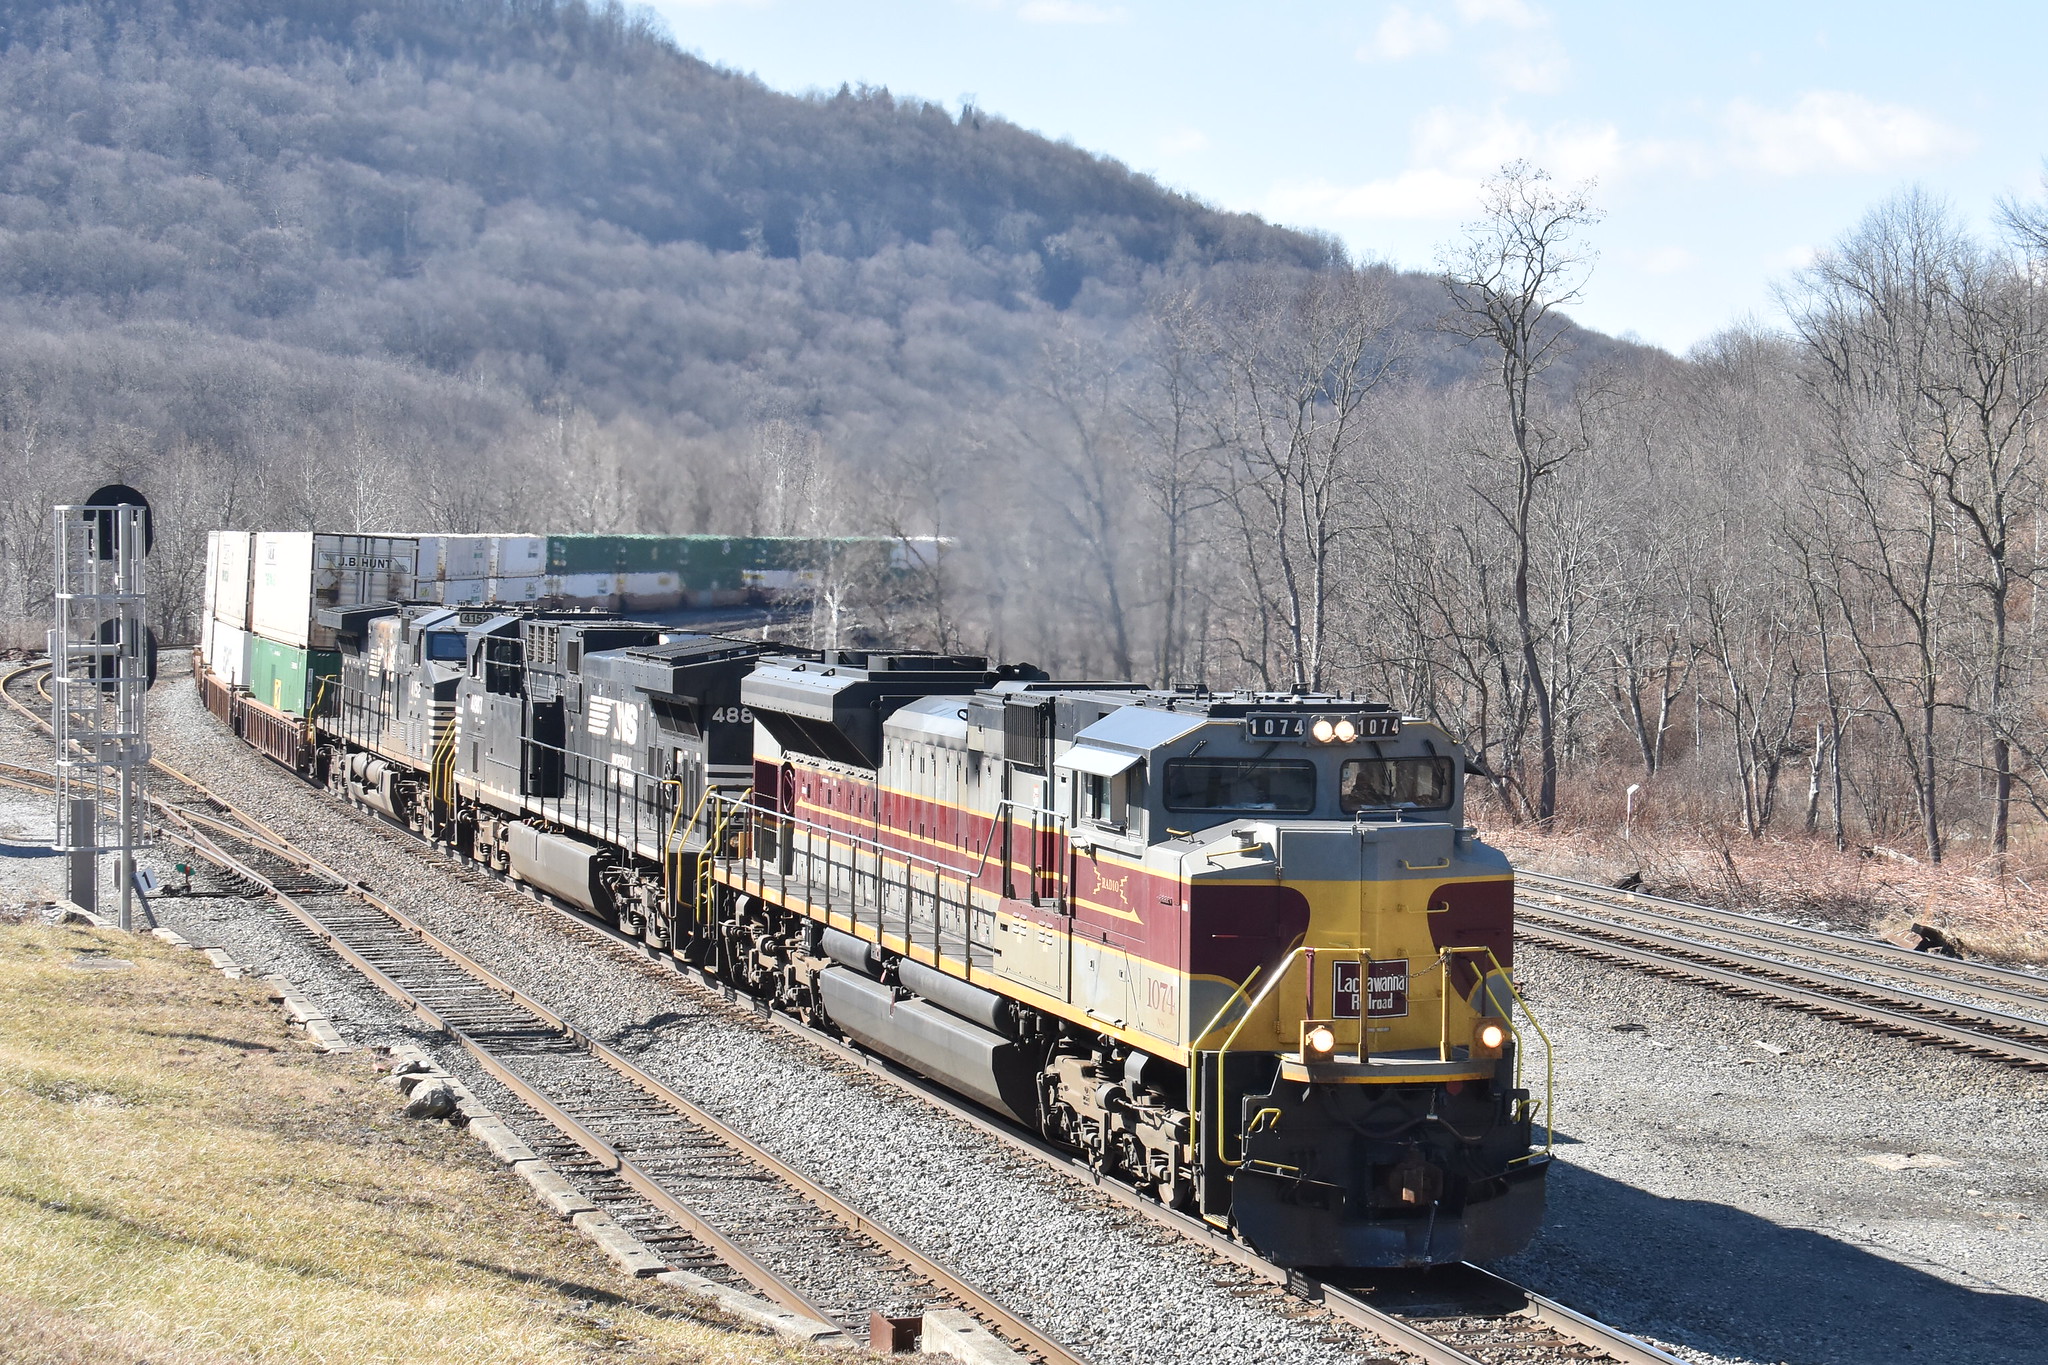
Norfolk Southern’s DL&W heritage unit, SD70ACe 1074, along with AC44C6M 4887 and 4152, leads eastbound train 20H at South Fork, Pennsylvania, on February 21, 2026. Doug Kroll photo.
Heritage paint is a 2026 fact on a working stack extra. Norfolk Southern’s predecessor schemes date from 2012; that program is the 2010s. The overview is fallen flags. South Fork is the old Pennsylvania Railroad Pittsburgh Line. Train 20H is how the eastern Class I actually looks: six-axle AC power, a rebuilt GEVO in the consist, and a train long enough that the photographer is standing in coal country to see the head end of an intermodal.
How they run
Precision Scheduled Railroading is the operating gospel. Longer trains. Fewer classification yards. Freight that is supposed to leave on a schedule instead of waiting for tonnage. The operating ratio is the scoreboard Wall Street still reads. Two-person road crews are the Class I norm. Positive Train Control is on the passenger and poison-inhalation-hazard mains; the statutory deadlines that put it there are the 2010s. Hunter Harrison’s campaign at Canadian Pacific and CSX is that decade too. What remains in 2026 is the method, applied with more or less rigor depending on the railroad and the year.
Critics still say the method trades resilience and local service for the ratio. The railroads still say the old service-heavy plant could not pay for itself. Both arguments are live. The photograph at Dallas is the result either way: a westbound on Union Pacific’s Texas plant, SD70ACe and Evolution-series GEs, the city in the background, no caboose, no second engine crew. Six-axle AC road power is what moves the tonnage. The locomotive encyclopedia is diesel locomotives.
The Surface Transportation Board
The Surface Transportation Board is the economic regulator of freight railroads. It hears mergers, line sales, and abandonments. It hears rate cases when a shipper can show market dominance and a revenue-to-variable-cost ratio over the statutory line that settled at 180 percent. It enforces the common-carrier obligation. It does not set every rate and it does not run the trains. The 1980 door those powers walk through is Staggers. The Board itself opened on January 1, 1996, when the Interstate Commerce Commission went out; that date is the 1990s.
Up to five members sit, appointed by the President and confirmed by the Senate. The Board often works with fewer. Major two-Class-I combinations are judged under rules issued in 2001 that ask applicants to show enhanced competition, not only the absence of harm, and to file a service-assurance plan. Those are the rules in force on the Union Pacific–Norfolk Southern application. How the 2001 rules were written is the 2000s. What they do in 2026 is this page. Common carrier as a legal idea is common carrier.
What they haul
Intermodal is the largest single revenue segment for the major railroads, about a quarter of the take. Chemicals, grain and food products, automobiles, metals, forest products, and aggregates pay most of the rest. Coal still moves—railroads still deliver on the order of 70 percent of the coal that reaches U.S. power plants—but it is not half the freight dollar. That mix shifted in the 2010s, when gas generation and environmental rules took the growth out of steam coal. The slide as a decade is the 2010s. The 2026 fact is that an eastbound coal extra and a westbound manifest can still meet on the old Baltimore & Ohio at Fairhope, Pennsylvania, on the same afternoon.
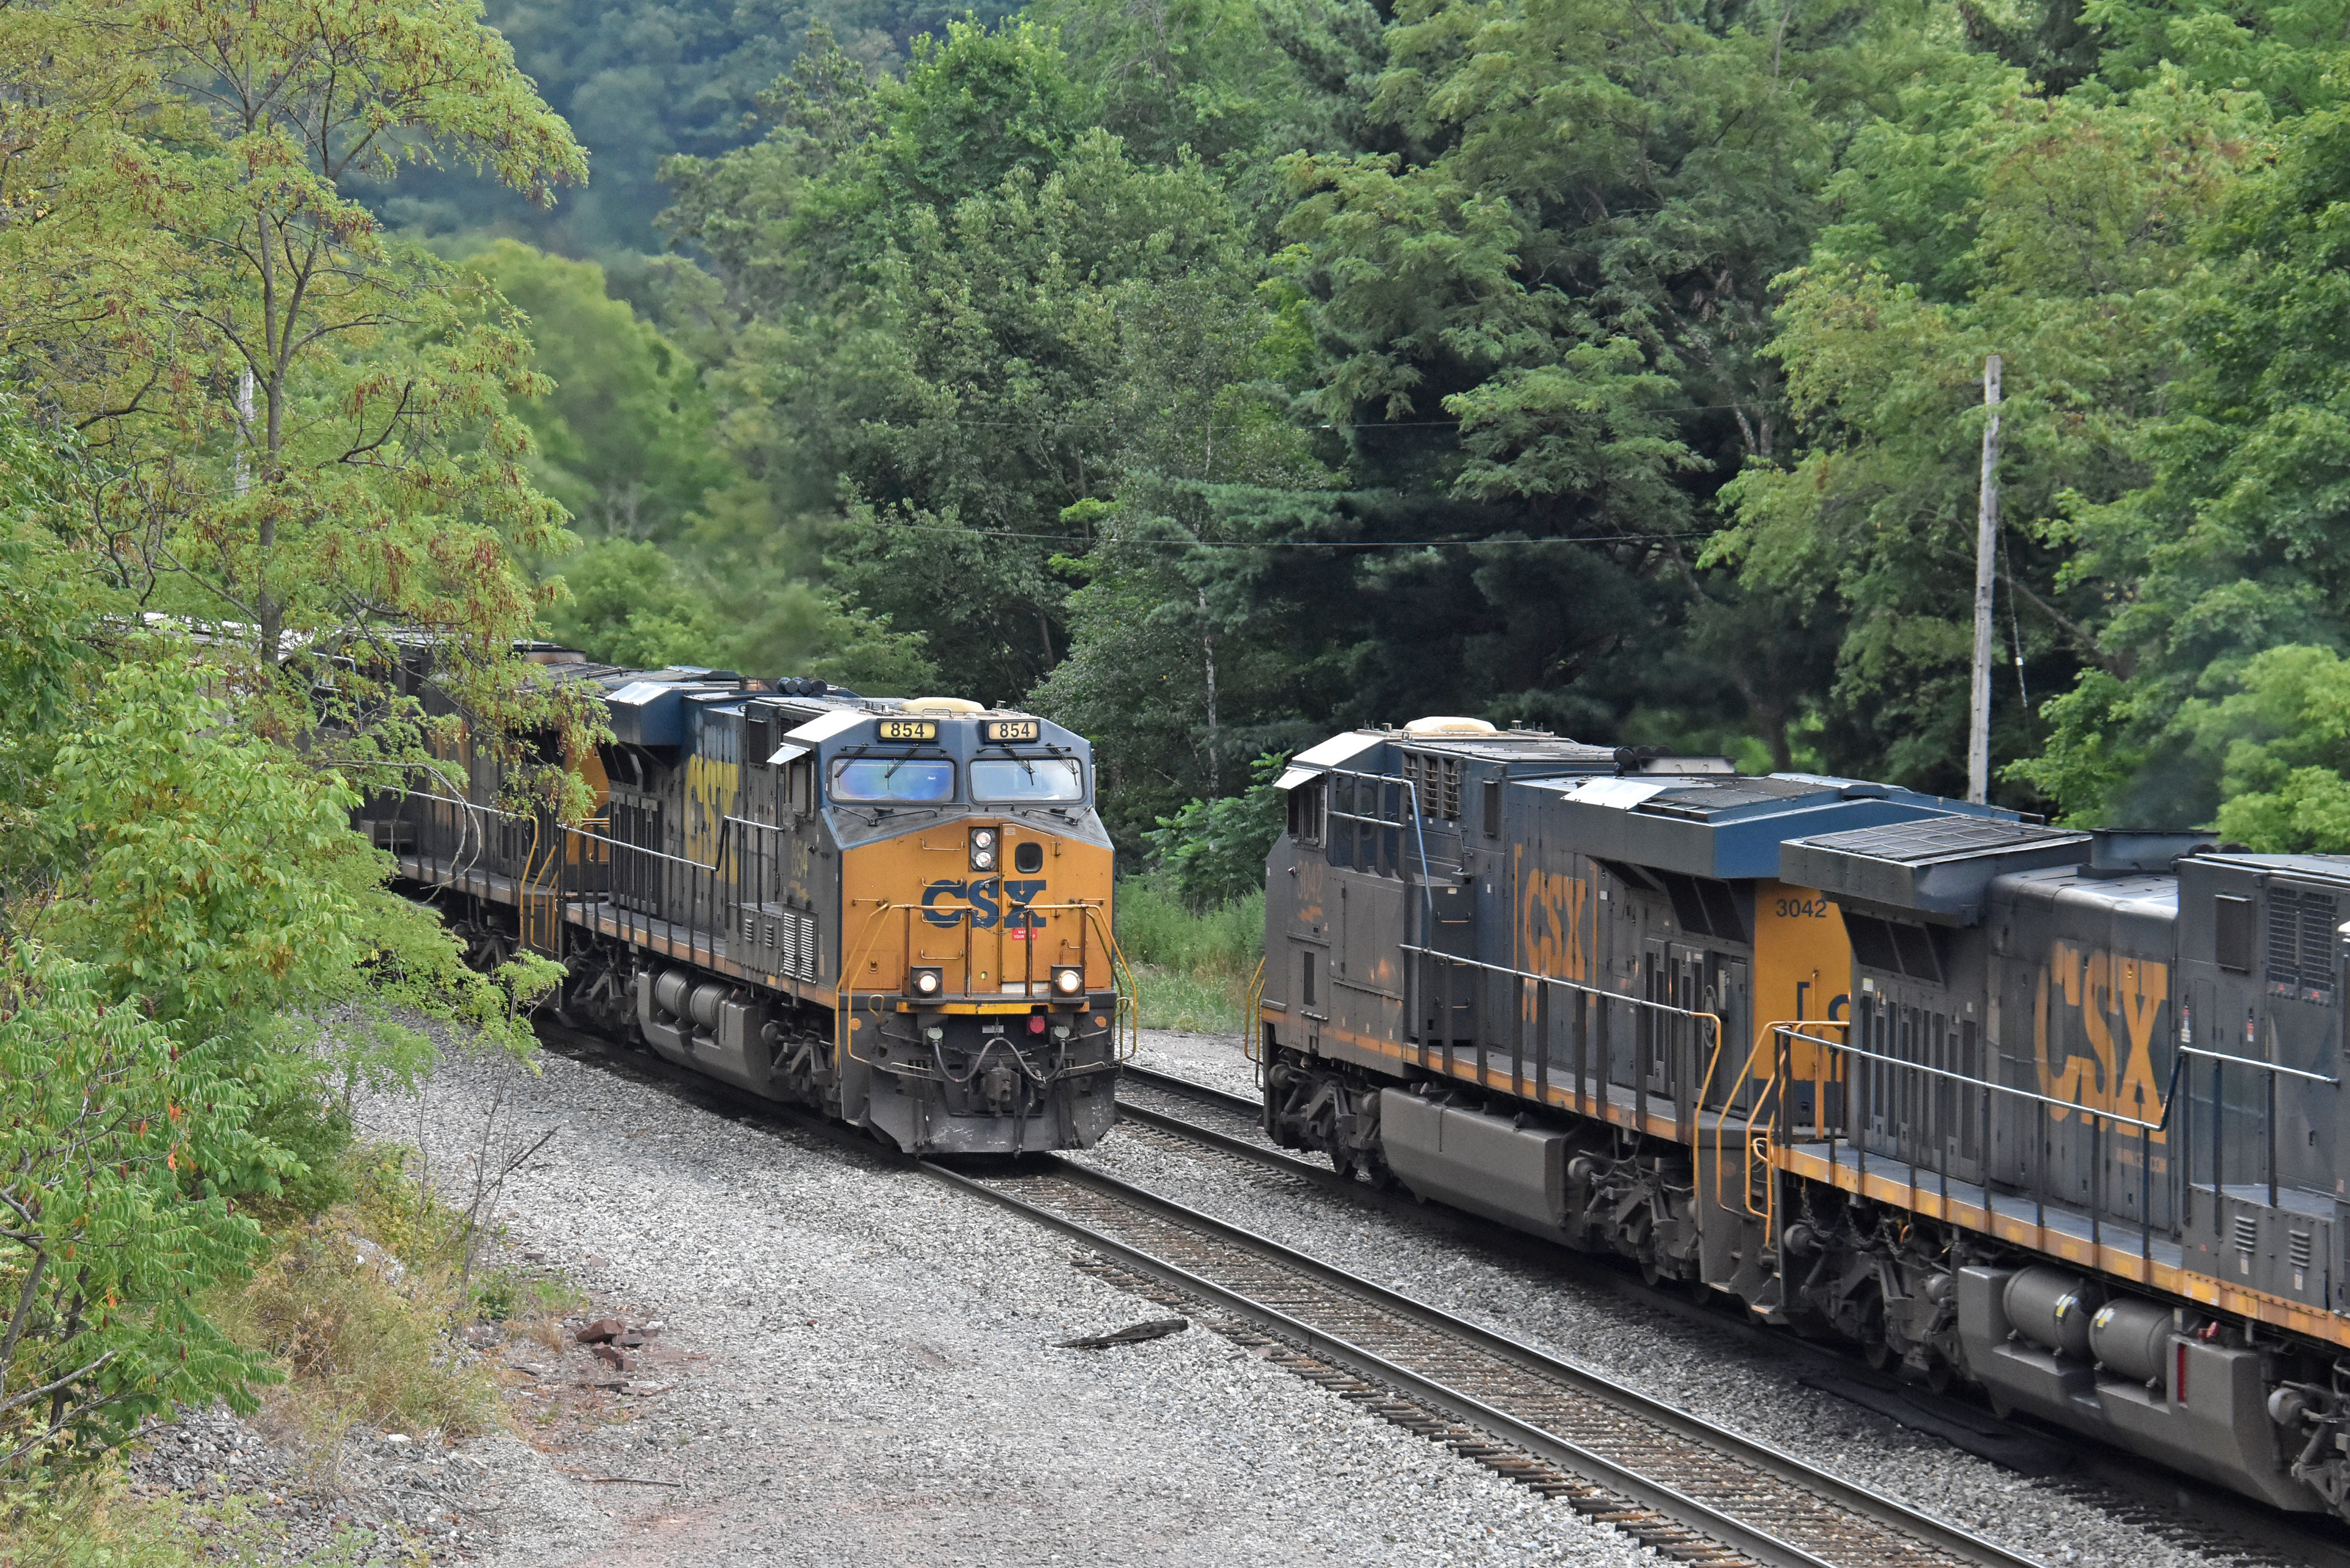
CSX ES44AH 854 is on a westbound manifest passing ES44AH 3042 on an eastbound coal drag along the old B&O main line at Fairhope, Pennsylvania, on July 26, 2024. Doug Kroll photo.
A typical year is about 1.5 billion tons. Inflation-adjusted revenue per ton-mile was 44 percent lower in 2024 than in 1981. From 1980 through 2024 the industry put about $840 billion of its own money back into track, bridges, locomotives, and cars. One ton moves nearly 500 miles on a gallon of diesel, on the Association of American Railroads’ usual yardstick.
Short lines and regionals
Class I miles of road are the decade-leaf series: 91,773 in 2020, down from 164,822 in 1980. A large part of that drop is sales, not scrap. About 615 Class II and III railroads run the rest of the plant—first mile, last mile, grain laterals, industrial switching, and a handful of regionals that look like small Class Is trackside. They account for roughly a third of the mileage and a thin slice of the revenue. The overviews are short lines and regionals.
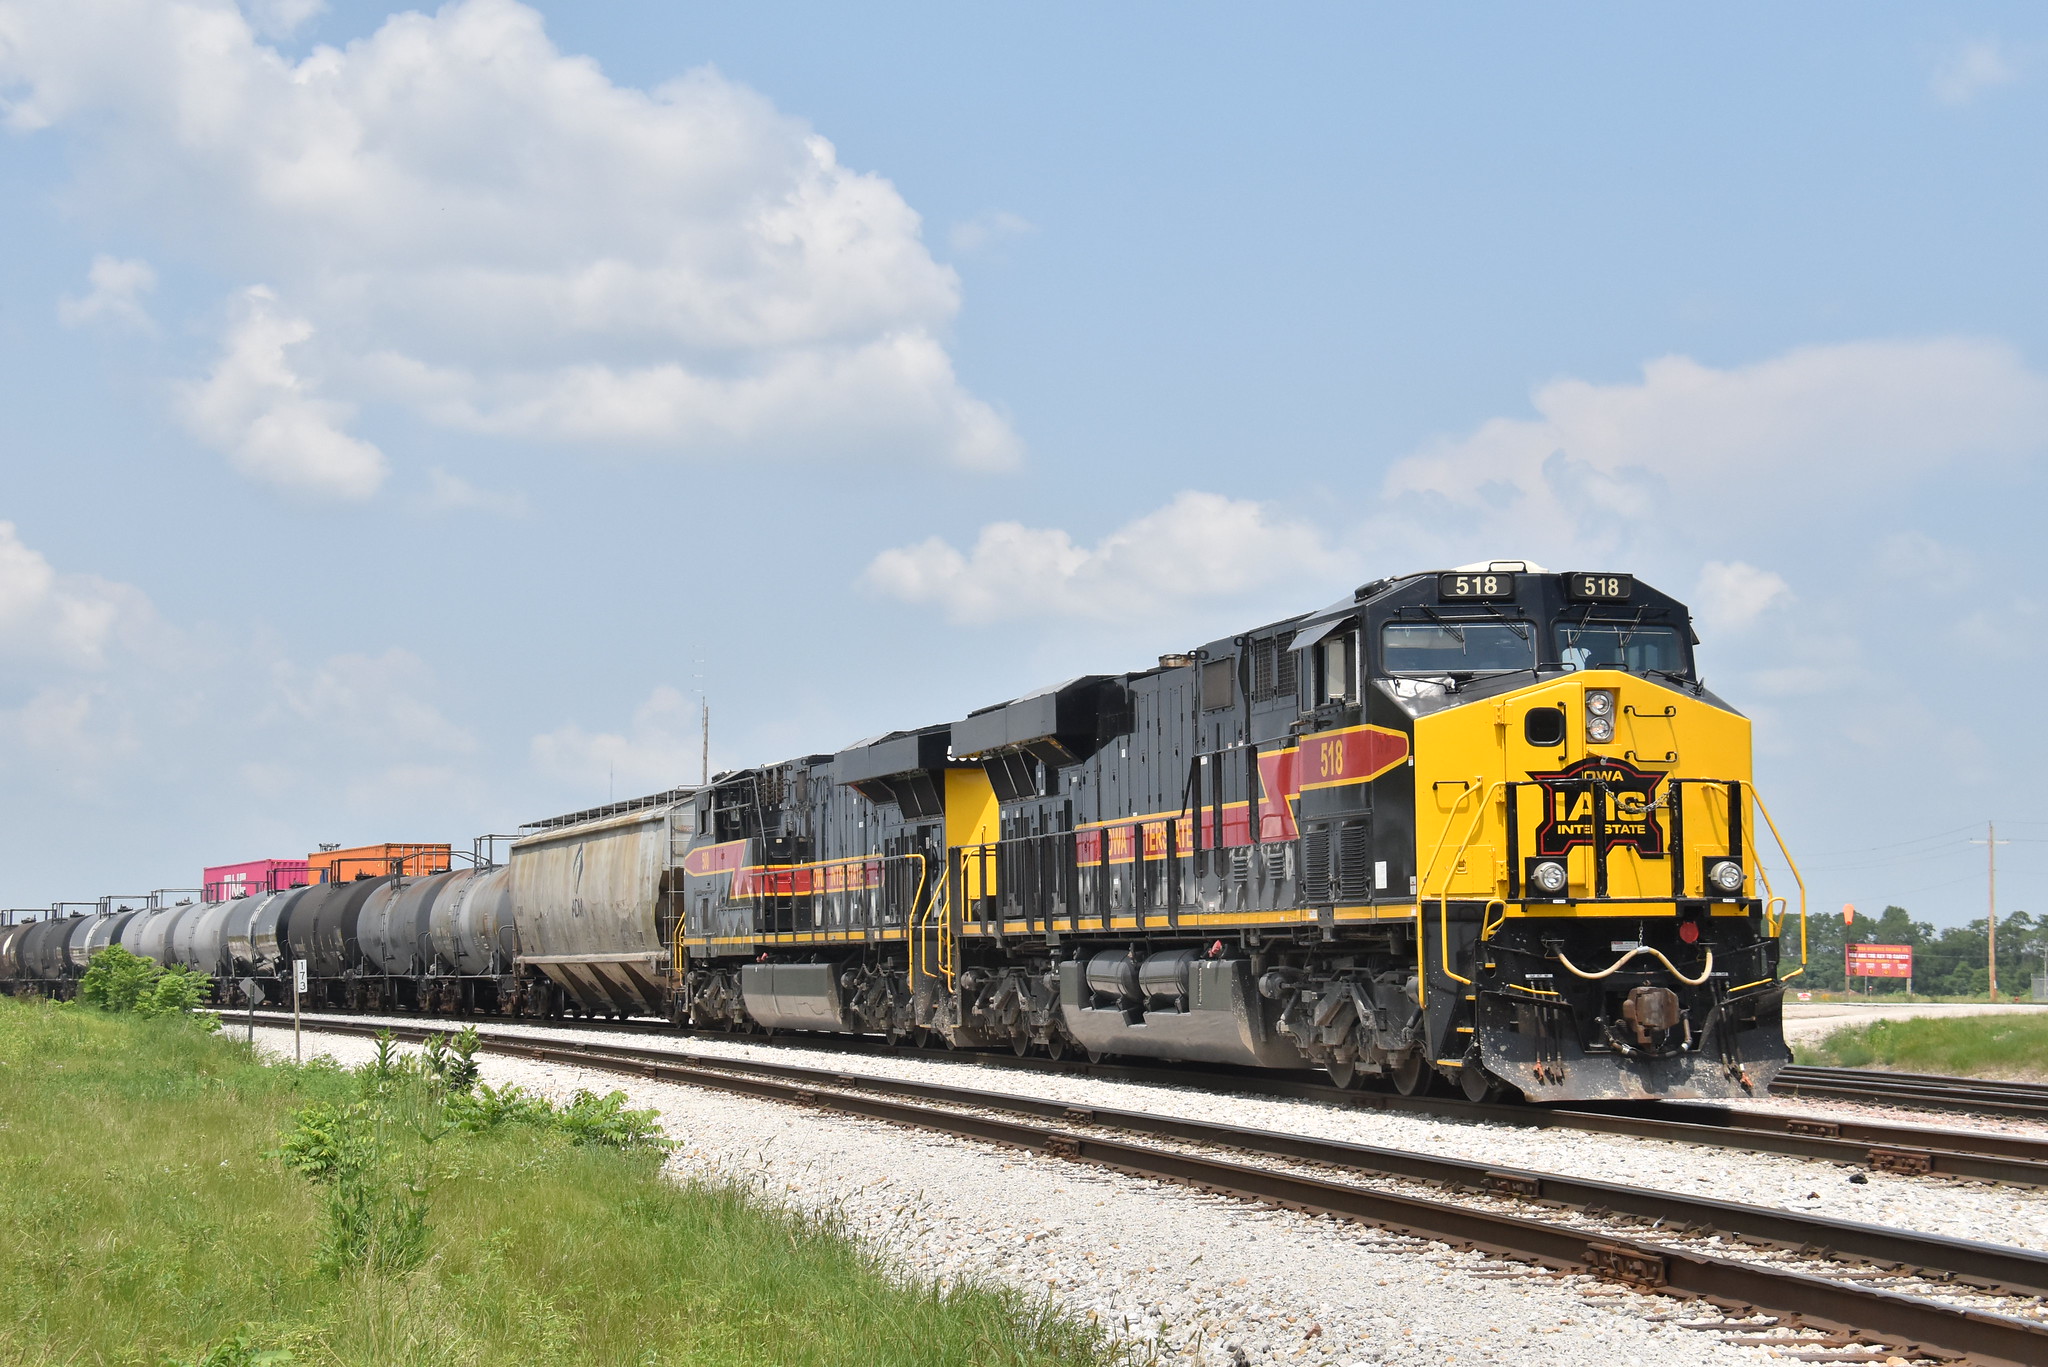
Iowa Interstate ES44AC 518 and 501 lead freight CBBI as the units make their setout and pickup at the Silvis, Illinois, yard on July 10, 2024. Doug Kroll photo.
Iowa Interstate is the former Rock Island Chicago–Council Bluffs main, a Class II regional that still interchanges with every North American Class I. Silvis is the old Rock Island shops. The 1980 liquidation is Rock Island and the 1980s. The 2026 fact is a pair of ES44ACs switching CBBI on a railroad that exists because shippers and a state refused to let that corridor die.
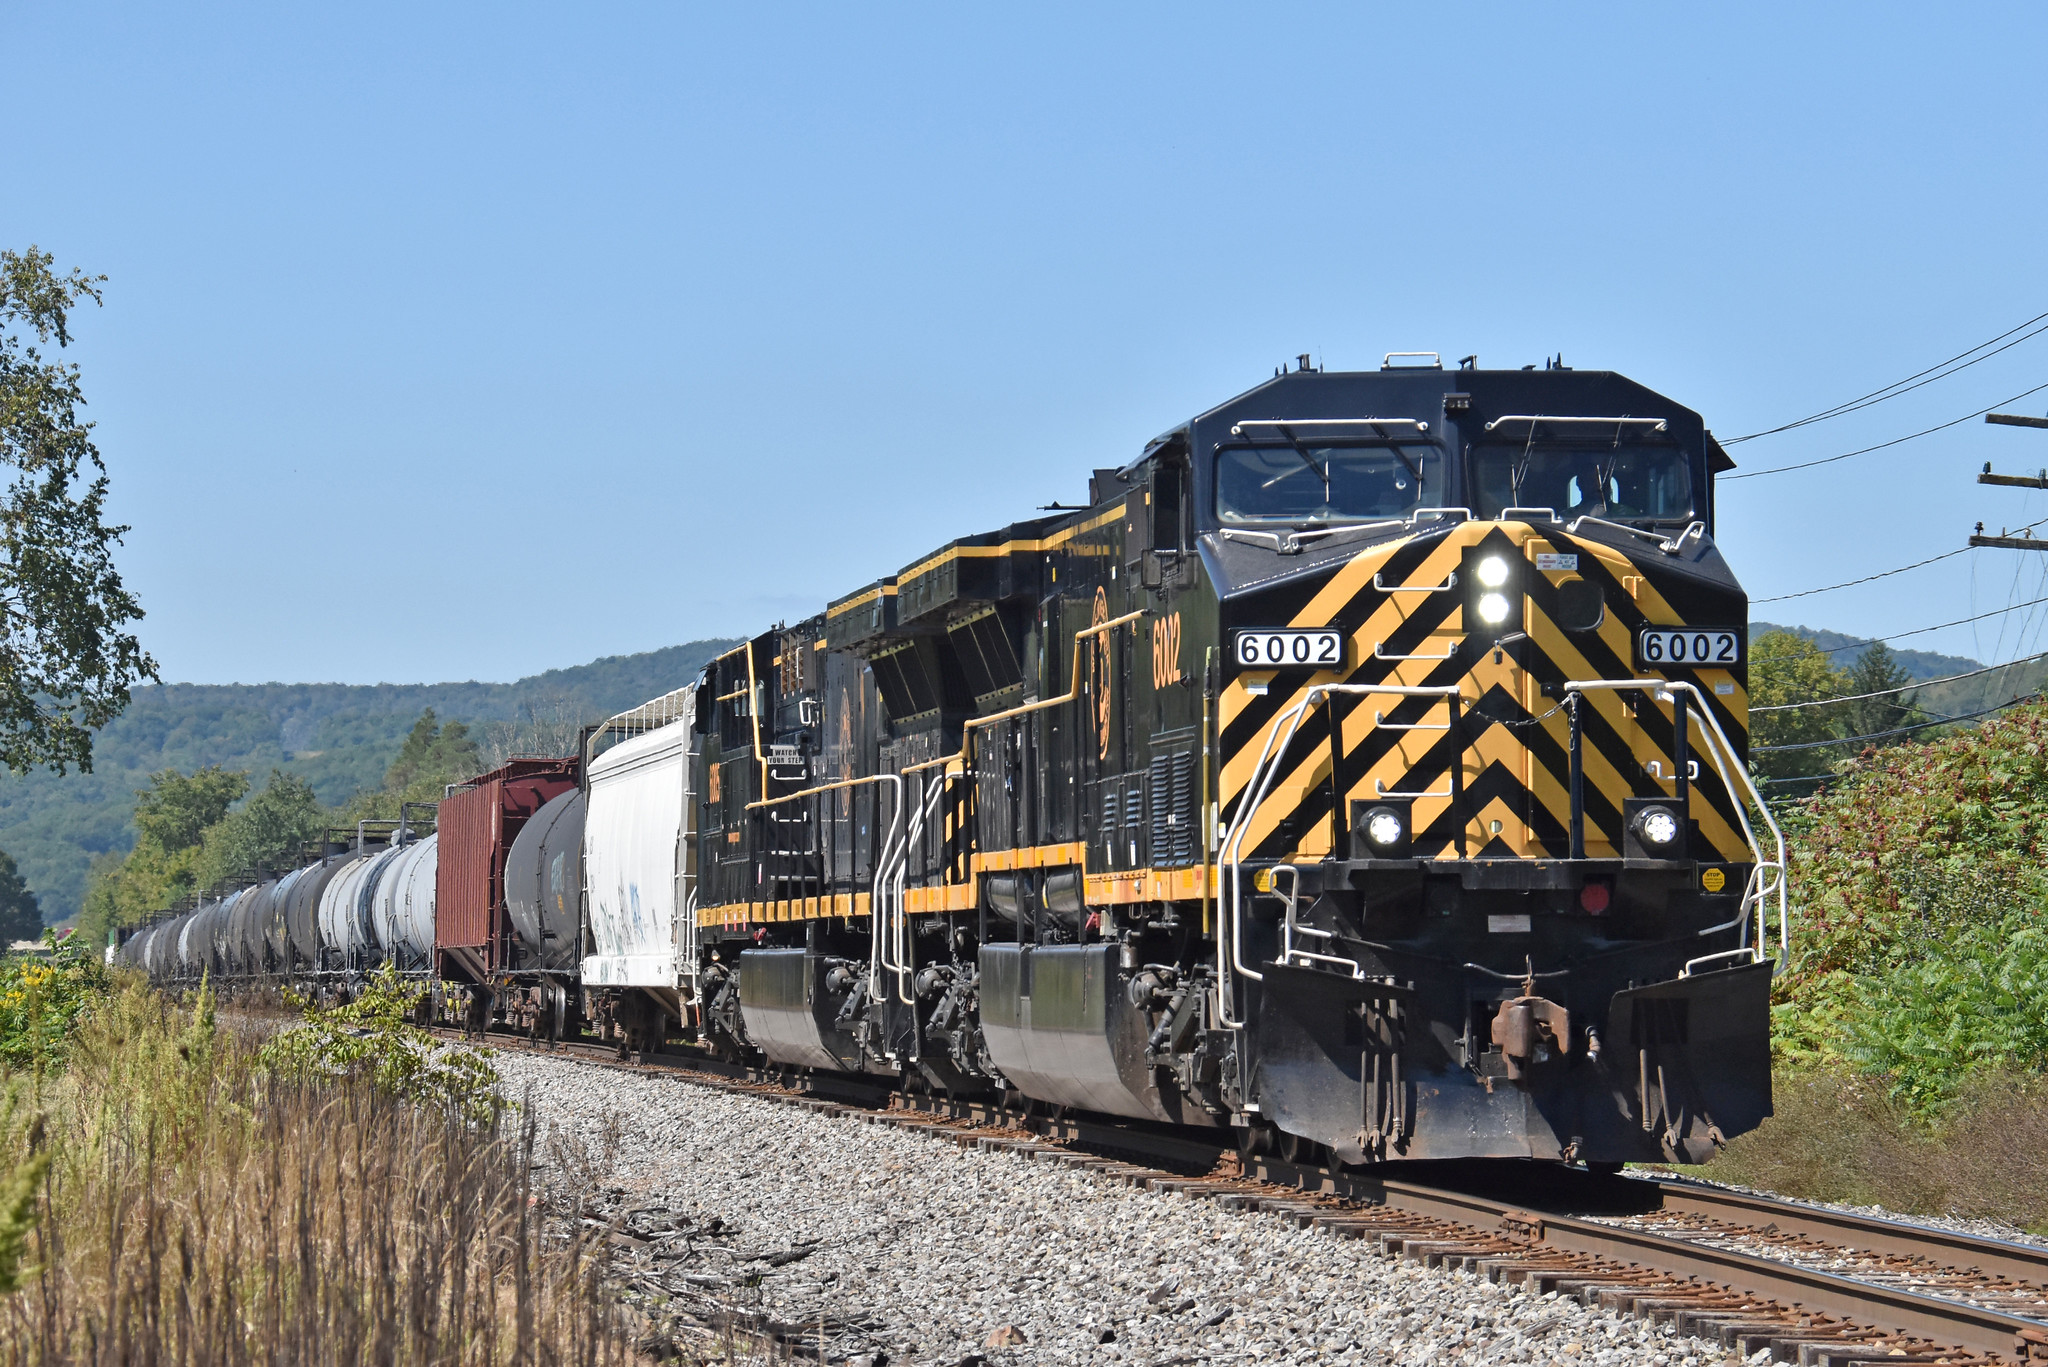
Western New York & Pennsylvania AC4460CW 6002 leads freight OL-3 eastbound near Allegany, New York, on September 15, 2023. The big GEs have since departed in favor of smaller, more nimble EMD power. Doug Kroll photo.
Western New York & Pennsylvania is the other half of the Staggers map: former Erie and Pennsylvania Railroad miles in western New York and northwestern Pennsylvania, run as a short-line regional in the Livonia, Avon & Lakeville family. Holding companies—Genesee & Wyoming, Watco, and the independents—own most of the rest. That industry is why a Class I can sell a branch and the grain elevator still has a railroad.
Passenger on freight rails
Amtrak owns a few hundred route-miles, mostly on the Northeast Corridor, and runs the rest of a 21,000-mile system on freight railroads. About 70 percent of Amtrak train-miles are on freight-owned track. Commuter agencies add their own contracts and their own iron. The company encyclopedia is Amtrak. The commuter map is commuter rail. Host congestion, slot agreements, and dispatching priority are the everyday passenger story in 2026. Named-train encyclopedias stay on their slugs.
The case still open
Union Pacific has agreed to buy Norfolk Southern. The companies announced it in 2025, about $85 billion, and told shareholders it would be the first single-company Atlantic–Pacific freight railroad in the United States. The Board accepted the application in 2026. As of September 2026 it has not decided. If the Board says yes, the six-name list will be wrong. If it says no, or yes with conditions that recast the map, that will be a later fact. The docket dates, the dollar figure, and the 2001-rules argument are the 2020s.
The 2026 industry is a smaller plant than 1980, a heavier one than 1980, and a six-railroad Class I club with a north–south Canadian in the middle and a transcontinental case on the table. Precision Scheduled Railroading is the method. The Board is the referee. Iowa Interstate at Silvis and Western New York & Pennsylvania at Allegany are why the miles the Class Is no longer wanted are still in the Official Guide at all.
Related reading on American-Rails.com
- Railroad History (USA) · Railroads In The 2020s · Staggers Act · Class I railroads
- BNSF · Union Pacific · CSX · Norfolk Southern · Canadian National · CPKC
- Short lines · Regionals · Iowa Interstate · Livonia, Avon & Lakeville
- Amtrak · Commuter rail · Railroad jobs · Diesel locomotives
- Fallen flags · Common carrier · Infrastructure · Railroads In The 2010s
Sources
- Association of American Railroads, Freight Rail Facts & Figures (network nearly 140,000 miles; six Class I railroads and about 615 short lines; Class I share of mileage, employees, and revenue; about 153,000 direct jobs; pay-and-benefit range $135,000–$190,000; about $25 billion private investment a year; about $840 billion reinvested 1980–2024; rates 44% lower in 2024 than in 1981; about 1.5 billion tons in a typical year; about 40% of long-distance ton-miles; intermodal about 25% of major-railroad revenue in 2023; Chicago hub; Amtrak train-miles on freight track)
- Association of American Railroads, Railroad Facts, national-network snapshot used on this page: 164,822 miles (1980) and 136,650 miles (2020). Class I miles of road 91,773 (2020) stay on the decade leaves
- Surface Transportation Board, Class I revenue threshold about $1.095 billion for 2025 (deflator / 49 C.F.R. Part 1201). Major-merger rules, Ex Parte 582 (Sub-No. 1), 2001, as the rules in force
- Joseph P. Schwieterman, When the Railroad Leaves Town (Official Guide community counts). Bill Yenne, Atlas of North American Railroads
- Live American-Rails Class I, company, short-line, regional, Amtrak, jobs, and decade pages as linked above. UP–NS docket dates on the 2020s page
Recent Articles


-
Norfolk & Western Diesel Roster (All-Time)
Oct 12, 26 11:59 PM
 Norfolk & Western diesel roster, all-time. 1,464 locomotives built new for the railroad, from the 1955 GP9s and RS-3s through the C36-7s, plus the merger fleets.
-
Norfolk & Western Steam Roster (Post 1900)
Oct 12, 26 11:52 PM
 Norfolk & Western steam since 1898. The Roanoke grid: 1,266 locomotives, the J, the A, and the Y, and the last road steam on May 7, 1960.
-
Norfolk & Western Railway: Map, Logo, Rosters, History
Oct 12, 26 11:45 PM
 The Norfolk & Western, from the City Point Railroad of 1838 to Norfolk Southern. Pocahontas coal, Roanoke steam, and the 1964 expansion.
-
Louisiana Railroad Museums (2026): A Complete Guide
Oct 12, 26 11:24 PM
 Louisiana railroad museums—the DeQuincy depot, the Long Leaf sawmill, Jackson’s model railroad, and Southern Pacific 745. Confirm hours on each site.
-
Michigan Railroad Museums (2026): A Complete Guide
Oct 12, 26 11:14 PM
 Michigan railroad museums—Pere Marquette 1225 at Owosso, Durand Union Station, The Henry Ford, and the Mount Clemens depot. Confirm hours on each site.
-
Mississippi Railroad Museums (2026): A Complete Guide
Oct 12, 26 10:52 PM
 Mississippi railroad museums—McComb’s rebuilt Illinois Central depot and Illinois Central 2542, and the Casey Jones museum at Water Valley. Confirm hours on each site.
-
The "E2b": PRR's Experimental Freight Electrics
Oct 12, 26 10:33 PM
 PRR class E2b: six GE B-B freight electrics, 4939–4944, 2,500 hp, 11 kV AC. Specifications, roster, and the 1964 scrap.
-
Alaska Railroad Museums (2026): A Complete Guide
Oct 12, 26 10:10 PM
 Alaska railroad museums—the Museum of Alaska in Wasilla, Tanana Valley No. 1 at Pioneer Park, and the Engine 557 shop. Confirm hours on each site.
-
Western and Atlantic Railroad: Map, History, Timetables
Oct 12, 26 09:55 PM
 The Western & Atlantic Railroad of the State of Georgia, authorized December 21, 1836, from Atlanta to Chattanooga. The state still owns the 137.33-mile line. CSX leases it. The through railroad opene…
-
Nashville, Chattanooga & St. Louis Steam Roster (Post 1900)
Oct 12, 26 09:52 PM
 Nashville, Chattanooga & St. Louis steam since 1900. Drury's class grid: Consolidations, 51 Mikados, three 2-8-8-2s, Pacifics, and 25 4-8-4s. Last steam was January 4, 1953.
-
Nashville, Chattanooga & St. Louis Diesel Roster (All-Time)
Oct 12, 26 09:27 PM
 Nashville, Chattanooga & St. Louis diesel roster, all-time. Switchers from 1941, 37 GP7s, and the F3s and F7s. The quantity column totals 132 locomotives.
-
Nashville, Chattanooga and St. Louis Railway: Map, History, Logo
Oct 12, 26 08:41 PM
 The Nashville, Chattanooga & St. Louis, the Dixie Line. Charter of December 11, 1845, the Cumberland tunnel, and the Louisville & Nashville merger of August 30, 1957.
-
Idaho Railroad Museums (2026): A Complete Guide
Oct 12, 26 02:44 PM
 Idaho railroad museums—Nampa’s 1903 depot, Wallace’s Northern Pacific depot, and Boise’s 1925 Union Pacific depot. Confirm hours on each site.
-
Hawaii Railroad Museums (2026): A Complete Guide
Oct 12, 26 12:50 PM
Hawaii railroad museums—the Hawaiian Railway Society at Ewa Beach and the Laupahoehoe Train Museum on the Big Island. Confirm hours on each site. -
Marietta and Cincinnati Railroad: Map, History, Timetable
Oct 12, 26 11:44 AM
 Marietta and Cincinnati Railroad, chartered March 8, 1845 as the Belpre & Cincinnati. Opened in April 1857, sold under foreclosure December 9, 1882, and succeeded by the Baltimore & Ohio Southwestern…
-
Tennessee Railroad Museums (2026): A Complete Guide
Oct 12, 26 11:39 AM
 Tennessee railroad museums—TVRM and Southern 4501 in Chattanooga, the Tennessee Central museum in Nashville, Casey Jones in Jackson, and the depots at Cookeville, Cowan, and Townsend.
-
Virginia Railroad Museums (2026): A Complete Guide
Oct 12, 26 09:40 AM
 Virginia railroad museums—Roanoke’s Virginia Museum of Transportation and the O. Winston Link Museum, the C&O center at Clifton Forge, and the depots in Richmond, Fairfax Station, Suffolk, Parksley, a…
-
Louisville & Nashville Diesel Roster (All-Time)
Oct 12, 26 12:15 AM
 Louisville & Nashville diesel roster, all-time. Switchers from 1939, the cab units, and EMD, Alco, and GE hoods through the SD50s. The quantity column totals 1948 locomotives, plus 29 yard slugs.
-
Louisville & Nashville Steam Roster (Post 1900)
Oct 11, 26 05:44 PM
Louisville & Nashville steam since 1900. Drury's class grid: Consolidations, 165 heavy Mikados, 42 Big Emma 2-8-4s, Pacifics, and 22 Mountains. Last steam January 1957. -
Louisville and Nashville Railroad: Map, Rosters, History
Oct 11, 26 05:39 PM
 Louisville & Nashville, the Old Reliable. Charter of March 5, 1850, Milton H. Smith, the 921-mile main line, Big Emma, and the December 29, 1982 merger. Steam and diesel rosters are companion pages.
-
Oregon Railroad Museums (2026): A Complete Guide
Oct 11, 26 05:19 PM
 Oregon railroad museums—the Oregon Rail Heritage Center, Brooks trolleys, Canby’s 1891 depot, Medford’s Willamette, and Train Mountain. Confirm hours on each site.
-
Texas Railroad Museums (2026): A Complete Guide
Oct 11, 26 05:15 PM
 Texas railroad museums—Frisco’s Big Boy 4018, Galveston’s Santa Fe depot, Temple’s 1911 station, Plano’s interurban, and Fort Worth & Denver 304. Confirm hours on each site.
-
Wisconsin Railroad Museums (2026): A Complete Guide
Oct 10, 26 11:51 PM
Wisconsin railroad museums—Green Bay’s Big Boy 4017 and Eisenhower’s A4, Mid-Continent at North Freedom, East Troy’s interurban, and the Riverside & Great Northern. Confirm hours on each site. -
Interstate Railroad (Virginia): Map, Roster, Logo, History
Oct 10, 26 11:22 PM
 Interstate Railroad, a Virginia coal road chartered February 18, 1896. Andover shops. Ten Alco RS3s, 30–39. Southern control in 1961. The company ended October 31, 1985.
-
North Carolina Railroad Museums (2026): A Complete Guide
Oct 10, 26 11:16 PM
North Carolina railroad museums—Spencer Shops, Wilmington’s Atlantic Coast Line 250, Hamlet’s Seaboard depot, and the New Hope Valley Railway. Confirm hours on each site. -
New Mexico Railroad Museums (2026): A Complete Guide
Oct 10, 26 10:54 PM
 New Mexico railroad museums—Santa Fe 2926 in Albuquerque, the Clovis depot, Alamogordo’s Toy Train Depot, and Belen. Confirm hours on each site.
-
New York Railroad Museums (2026): A Complete Guide
Oct 10, 26 09:33 PM
 New York railroad museums—Phoenicia, Medina’s New York Central freight house, the Transit Museum, Long Island 35 and 39, and GG1 4933. Confirm hours on each site.
-
Columbia, Newberry & Laurens Railroad: History, Timetable, Roster
Oct 10, 26 09:08 PM
 Columbia, Newberry & Laurens Railroad, Columbia to Laurens, 75 miles. Chartered in 1885. Five Atlantic Coast Line GP7s, 100–104. Merged into the Seaboard System on April 30, 1984.
-
New Haven Diesel Roster (All-Time)
Oct 10, 26 06:35 PM
 New Haven diesel roster, all-time. 558 road numbers: 60 DL-109s, 30 FA-1s, 27 PA-1s, 60 FL9s, and the switchers from HH600 0900. Serials and order numbers.
-
New Haven Steam Roster (Post 1900)
Oct 10, 26 06:31 PM
 New Haven steam since 1900. Drury's class grid: 226 Moguls, 33 Mikados, 50 Santa Fes, 70 Mountains, 141 Pacifics, and 10 Hudsons. Last fan trip July 19, 1953.
-
New Haven Railroad: Rosters, Map, Logo, History, Trains
Oct 10, 26 06:26 PM
 New York, New Haven and Hartford. The Shore Line, Hell Gate, the 1952 map at 1,838.89 miles, and the railroad Penn Central took at 11:59:59 p.m. on December 31, 1968.
-
C&O's 4-6-4 "Hudson" Locomotives (Class L): Specs, Roster, History
Oct 10, 26 05:36 PM
 Chesapeake & Ohio Class L 4-6-4 Hudsons. Eight L-2s, five L-1 rebuilds, five L-2-As. Specs, Baldwin works numbers, and the roster. No. 490 survives.
-
Alton Railroad: Map, History, Timetables
Oct 09, 26 10:31 PM
 Alton Railroad, chartered February 27, 1847 as the Alton & Sangamon. Chicago, St. Louis, and Kansas City, the 1937 Official Guide, and the May 31, 1947 merger into the Gulf, Mobile & Ohio.
-
Mobile & Ohio Steam Roster (Post 1900)
Oct 09, 26 12:26 PM
 Mobile & Ohio steam since 1900. Drury's class grid: 48 six-wheel switchers, 107 Ten-Wheelers, 15 Consolidations, 58 Mikados, and 14 Pacifics. Last revenue steam October 7, 1949.
-
Mobile & Ohio Railroad: History, Map, Timetable
Oct 09, 26 11:31 AM
 Mobile & Ohio Railroad, chartered in 1848. Columbus on April 22, 1861, the Cairo & St. Louis, the March 1940 Official Guide, and the September 13, 1940 merger into the Gulf, Mobile & Ohio.
-
Gulf, Mobile & Northern Steam Roster (Post 1900)
Oct 09, 26 10:42 AM
 Gulf, Mobile & Northern steam since 1900. Drury's class grid: Ten-Wheelers, Mikados, Russian Decapods, Pacifics 425 and 426, and three light 4-8-2s. Last revenue steam October 7, 1949.
-
Gulf, Mobile & Ohio Diesel Roster (All-Time)
Oct 09, 26 10:41 AM
 Gulf, Mobile & Ohio diesel roster, all-time. The 1935 boxcab, DL-107s, 55 FA-1s, F3s and F7s, the Ingalls 4-S, GP30s through GP38-2s, and 21 SD40s. Serials and order numbers.
-
Gulf, Mobile & Northern Railroad: History, Rebel Route
Oct 09, 26 10:36 AM
 Gulf, Mobile & Northern, from the 1890 Mobile, Jackson & Kansas City to the Rebel and the September 13, 1940 merger into the Gulf, Mobile & Ohio. Steam roster is the companion page.
-
Gulf, Mobile & Ohio Railroad: Map, Photos, Trains, History
Oct 08, 26 11:48 PM
 Gulf, Mobile & Ohio, chartered in 1938 and merged September 13, 1940. The Mobile & Ohio, the Alton on May 31, 1947, the Rebel Route, and Illinois Central Gulf on August 10, 1972.
-
New Jersey Railroad Museums (2026): A Complete Guide
Oct 08, 26 11:37 PM
 New Jersey railroad museums—Whippany, Maywood, Pine Creek, Mahwah’s Erie depot, Phillipsburg, and Boonton. Confirm hours on each site.
-
New Hampshire Railroad Museums (2026): A Complete Guide
Oct 08, 26 11:34 PM
 New Hampshire railroad museums—North Conway, the Flying Yankee, Ashland, Gorham, Raymond, and Sandown. Confirm hours on each site.
-
Missouri Railroad Museums (2026): A Complete Guide
Oct 08, 26 11:00 PM
 Missouri railroad museums—the National Museum of Transportation, Patee House, Frisco 4524, the Chicago & Alton depot, and Marceline. Confirm hours on each site.
-
Milwaukee Road X3800: Deer Lodge’s Shop Goat
Oct 08, 26 04:28 PM
 Milwaukee Road X3800, the a home-built shop goat that served the Deer Lodge, MT yard. It was a 220-volt DC switcher, powered through an extension cord that moved electrics into a roundhouse where the…
-
Key West Extension (Overseas Railroad): History, Construction, Decline
Oct 08, 26 03:59 PM
 Henry Flagler's Overseas Railroad, Miami to Key West, 1905–1935. The Seven Mile Bridge, the 1935 Labor Day Hurricane, and the road that became U.S. 1.
-
Florida East Coast Steam Roster (Post 1900)
Oct 08, 26 02:34 PM
 Florida East Coast steam since 1897. Seventeen Ten-Wheelers, twenty Atlantics, eighty-seven Pacifics, ninety Mountains, fifteen Mikados, and the switchers.
-
Florida East Coast Diesel Roster (All-Time)
Oct 08, 26 02:12 PM
 Florida East Coast diesel roster, all-time. E units from 1939, F3s, BL2s, GP7s and GP9s, the GP40-2 orders, 22 SD40-2s, and 24 ES44C4s. Serials and EMD order numbers.
-
Florida East Coast Railway: Map, History, Rosters
Oct 08, 26 01:46 PM
 Florida East Coast Railway, Henry Flagler's line from Jacksonville to Miami and Key West. Receivership in 1931, the 1963 strike, Grupo México in 2017, and Brightline on the same track.
-
Minnesota Railroad Museums (2026): A Complete Guide
Oct 08, 26 10:32 AM
Minnesota railroad museums—the Lake Superior Railroad Museum, Two Harbors, Jackson Street, Willmar’s Great Northern 2523, and Currie. Confirm hours on each site. -
Maine Railroad Museums (2026): A Complete Guide
Oct 08, 26 09:24 AM
 Maine railroad museums—Seashore Trolley, the two-foot lines at Portland, Alna, and Phillips, Boothbay, and the Bangor & Aroostook depots. Confirm hours on each site.
-
Massachusetts Railroad Museums (2026): A Complete Guide
Oct 08, 26 12:08 AM
 Massachusetts railroad museums—Berkshire Scenic at Lenox, Shelburne Falls trolley No. 10, Edaville, Chatham’s 1887 depot, and Lowell. Confirm hours on each site.