Canadian National Marks 30 Years Since Privatization
Published: February 25, 2026
MONTREAL — Canadian National Railway is marking a milestone that helped redefine not only the company, but the modern Canadian freight-rail landscape: 30 years since CN’s 1995 initial public offering (IPO) ended its status as a federal Crown corporation. In a statement released in November 2025, CN noted that on November 17, 1995, its shares began trading on the Toronto Stock Exchange and New York Stock Exchange, raising about C$2.25 billion—at the time the largest IPO in Canadian history.
To commemorate the anniversary, CN leadership participated in bell-ringing ceremonies tied to the public markets that have defined the company’s modern era. Industry coverage described CEO Tracy Robinson and board chair Shauneen Bruder as helping mark the moment at the exchanges, underscoring how closely CN’s identity is now linked to investor expectations, operating discipline, and growth beyond Canada’s borders.
Yet CN’s 30-year “public company” chapter is only part of a much longer story—one rooted in the early 20th century, when Ottawa moved to knit together bankrupt and strategically important railways into a single national system. For decades, CN was not merely a railroad but a nation-building instrument: a government-owned network expected to serve regional development goals, maintain passenger service, and provide jobs—often while competing with a private rival, Canadian Pacific.
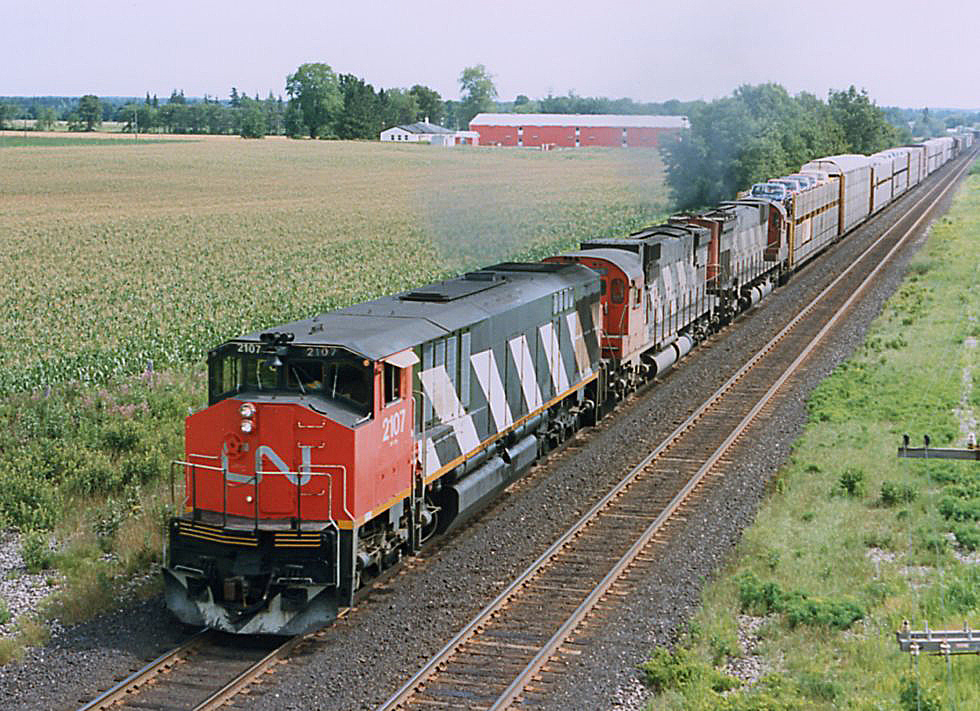 Canadian National HR-616 #2107, M636 #2328, and a C630 are westbound at Princeton, Ontario on August 1, 1987. Doug Kroll photo.
CN’s privatization was the culmination of a broader federal push in the early-to-mid 1990s to reduce public exposure to commercial risk and encourage market-driven efficiency in state-owned enterprises. The legal foundation was the CN Commercialization Act, enacted in July 1995, setting the stage for the November 1995 IPO and the transfer of federal shares to private investors.
The Act and accompanying policy framework were notable for safeguards designed to preserve a “Canadian anchor” even after privatization. Among the best-known features: requirements ensuring CN’s headquarters remains in Montreal and a share-ownership cap (commonly cited as limiting any one shareholder to 15%) intended to prevent a single controlling owner from dominating the company.
In CN’s own 30th-anniversary messaging, the company framed privatization as the start of a modern reinvention: a shift from a state-owned system often perceived—fairly or not—as bureaucratic and politically constrained, to a railroad compelled to compete on service, cost, and performance.
Why CN existed in the first place: the nationalized “people’s railway”
To understand why 1995 mattered, you have to go back to the crisis years surrounding the First World War and its aftermath.
CN’s roots lie in a wave of railway financial collapses and government interventions. Several major systems had overbuilt, overleveraged, or simply could not sustain returns in a changing economy. The federal government took control of struggling lines—most notably the Canadian Northern Railway—and consolidated them with other government-owned railways into a new national entity. This process ultimately led to the incorporation of Canadian National Railways in 1919, with major consolidation steps continuing into the early 1920s.
The Canadian Encyclopedia describes CN as one of the defining transportation systems in the country—created through government action and ultimately becoming the longest railway system in North America by route reach, with an outsized role in Canadian economic integration.
During the nationalized decades, CN was expected to do more than maximize profit. It was frequently tasked—explicitly or implicitly—with goals like:
- maintaining service to thinly populated regions,
- operating extensive passenger trains,
- supporting wartime and postwar logistics,
- and acting as a national infrastructure backbone even when some segments were marginal on a strict business basis.
That “public mission” produced accomplishments, but also structural tensions. Governments—of all political stripes across the century—were pulled between investing in rail modernization and using CN to meet social and regional policy objectives.
CN’s Crown corporation era
From the 1920s onward, CN operated as a sprawling national system with both freight and passenger responsibilities. Over time, CN absorbed multiple predecessor railways and standardized operations across an enormous geography.
CN also became known for innovations that, while sometimes born from competitive pressure with CP, reflected the unique incentives of a national carrier. One of the most famous examples was CN’s early radio initiatives, which helped pioneer passenger-focused onboard services and contributed to Canada’s broader broadcasting history.
Passenger service was a defining part of the CN identity through much of the 20th century, but that began to change late in the 1970s. In 1978, many of CN’s intercity passenger responsibilities were shifted to Via Rail, created as a Crown corporation to consolidate passenger operations in Canada.
By the late 20th century, CN—like many railways—faced the hard realities of changing freight markets, deregulation trends, competition from trucks, and the rising cost of maintaining marginal routes. Those pressures sharpened debates about whether a government-owned CN could move fast enough and cut deeply enough to remain globally competitive.
The “before and after” of 1995: what privatization changed in practice
CN’s IPO did not merely change who owned the shares; it changed how the company was managed, measured, and incentivized.
As a public company, CN could more readily pursue network rationalization, capital discipline, and performance targets shaped by investor expectations. The company and outside observers have often highlighted aggressive modernization and management streamlining during the post-privatization years as key to improved financial outcomes.
The decade after privatization also set the stage for CN’s strategic expansion into the United States, which would come to define the railroad as a continental freight carrier rather than solely a Canadian east–west system. One pivotal move was the 1998 acquisition of Illinois Central, which strengthened CN’s north–south corridor linking Canada to the U.S. Gulf region via Chicago—reshaping CN’s commercial geography and traffic mix.
From a policy standpoint, Transport Canada continues to cite CN’s privatization framework as distinctive among major divestitures—particularly the statutory provisions that preserved certain public-interest constraints (such as language obligations and structural conditions) even after the company became privately owned.
Key dates at a glance
- 1919: Canadian National Railways incorporated as the federal government consolidates multiple troubled and government-owned systems.
- 1978: Via Rail assumes many intercity passenger services previously operated by CN.
- July 1995: CN Commercialization Act enacted, enabling privatization framework.
- Nov. 17, 1995: CN IPO launches on TSX/NYSE, raising about C$2.25B.
- Nov. 2025: CN marks 30th anniversary of privatization with public celebrations and reflections.
Marking 30 Years
In CN’s November 2025 release, the company emphasized the scale and symbolism of the 1995 offering: a Crown corporation became a publicly traded enterprise overnight, and the IPO proceeds—about C$2.25 billion—were large enough to register as a national financial event, not just an industry footnote.
That anniversary framing matters because CN’s contemporary identity—precision operations, scheduled railroading-era discipline (in the broad industry sense), and an integrated Canada-U.S. network—is often contrasted with the older perception of CN as a government-directed system. The company’s 30-year message in effect argues that the post-1995 model unlocked the ability to reinvest, compete, and grow at a tempo difficult under Crown ownership.
At the same time, CN’s very existence is a reminder that Canadian railroading was shaped as much by public policy as private capital. CN was built out of national necessity—created to stabilize essential transportation infrastructure during an era when rail was the primary long-distance land transport mode and multiple private railways had failed.
Legacy
CN’s 30th anniversary of privatization is ultimately an anniversary of transformation—but it also serves as an occasion to revisit the company’s dual legacy.
- As Canadian National Railways (CNR) in its early decades, it was the “people’s railway” in both slogan and function: a federally owned system tasked with making a far-flung country work as an integrated economy and society.
- As modern CN, it has become one of North America’s most important freight networks—transcontinental in Canada and deeply embedded in U.S. supply chains—operating under market rules, shareholder scrutiny, and a strategy that treats Canada-U.S. connectivity as central rather than incidental.
The 1995 IPO did not erase CN’s public-era footprint—many of its routes, terminals, and strategic corridors were forged in the nationalized years. But it did mark a fundamental change in purpose: from a state enterprise balancing national policy priorities to a corporation designed to generate returns by competing for freight in a continental marketplace.
Recent Articles


-
Bessemer & Lake Erie Railroad: "The Bessemer Road"
Sep 15, 26 05:20 PM
 Bessemer & Lake Erie—Bear Creek 1865, Carnegie 1897, U.S. Steel 1901. Ore south from Conneaut, coal north. 2-10-4s, Missabe sister road. CN May 10, 2004. Complete corporate history.
-
Bangor and Aroostook Railroad: "Serving Northern Maine"
Sep 15, 26 05:05 PM
 Bangor & Aroostook—chartered February 13, 1891, first trains January 1, 1894. Potatoes, paper, Searsport, State of Maine reefers. MM&A 2003, Lac-Mégantic 2013, CP 2020, CPKC today. Complete co…
-
Baltimore & Ohio Chicago Terminal Railroad: Map and History
Sep 15, 26 03:11 PM
 B&OCT—formed January 6, 1910 to buy Chicago Terminal Transfer. Grand Central, Barr Yard, 78 route-miles. Assigned B&O steam. Complete diesel roster. CSX paper subsidiary, mark BOCT.
-
The "Alphabet Route" (Railroad): Photos and History
Sep 15, 26 02:53 PM
 Alphabet Route—eight railroads, not one company. P&WV to Connellsville February 11, 1931. Alpha Jets Chicago/St. Louis–New York/Boston. NKP, W&LE, P&WV, WM, Reading, CNJ, L&HR, New Hav…
-
Milwaukee Road Livestock Operations: Cattle, Dakotas & Montana
Sep 15, 26 02:36 PM
 Milwaukee Road livestock traffic—Dakota and Montana cattle, Iowa hogs, Chicago markets, 28-hour law, head-end stock cars. By 1974 mostly Montana. Rick Burn’s Helena speech. Operations history, not the…
-
Spirit of Jasper Ride & Dine (2026): Season Pause
Sep 15, 26 02:29 PM
 Spirit of Jasper Ride & Dine in Jasper, Indiana—seated meal on board. Operator: not running public trains for 2026. Depot remains open as a rental. Confirm on spiritofjaspertrain.com.
-
South Carolina Canal & Rail Road Company: Map and History
Sep 15, 26 01:59 PM
 South Carolina Canal & Rail Road—chartered December 19, 1827. Best Friend of Charleston, 136 miles Charleston–Hamburg October 1833, Aiken inclined plane. South Carolina Railroad 1844, Southern 189…
-
The Practice of Double-Heading: The Steam Era
Sep 15, 26 01:43 PM
 Doubleheading—two locomotives on the point, each with its own steam crew. Not a rear helper, not diesel MU. How it worked, PRR 1877, mountain grades, and what MU ended.
-
Mohawk and Hudson Railroad: Map, Pictures, Locomotives
Sep 15, 26 01:20 PM
 Mohawk & Hudson Railroad—New York’s first railroad, chartered April 17, 1826. DeWitt Clinton, inclined planes, Albany & Schenectady 1847, first New York Central May 17, 1853. Complete corporat…
-
Essex Clipper Dinner Train (2026): Dates, Tickets & What to Expect
Sep 15, 26 01:09 PM
 2026 Essex Clipper Dinner Train in Essex, CT—2.5 hours, four-course meal $129.99, 18+. Fall dates through Oct. 25. Confirm on essexsteamtrain.com.
-
Camden & Amboy Railroad: Map, History, Photos
Sep 15, 26 12:53 PM
 Camden & Amboy Railroad—chartered February 4, 1830. Joint Companies monopoly with the Delaware & Raritan Canal, John Bull, T-rail. United New Jersey 1872, PRR 999-year lease 1871. Complete corpora…
-
Cafe Lafayette Dinner Train (2026): Dates, Tickets & What to Expect
Sep 15, 26 12:47 PM
2026 Cafe Lafayette Dinner Train in North Woodstock, NH—2 hours, 20 miles, five-course meal from $125. May–October. Confirm on nhdinnertrain.com. -
Christmas Train Ride Locations (2026): A Complete Guide
Sep 15, 26 10:47 AM
 2026 Christmas train rides by state—Santa, North Pole Express, and holiday trains. Not Polar Express. State guides and product pages. Confirm dates on each railroad.
-
Baltimore & Ohio Railroad: Linking 13 Great States With The Nation
Sep 15, 26 10:22 AM
 Baltimore & Ohio Railroad—first U.S. common carrier, chartered February 28, 1827. Wheeling 1853, Chicago 1874, C&O control 1963, Chessie 1973, into CSX April 30, 1987. Complete corporate history.
-
Delaware & Hudson Railway: The Bridge Line
Sep 15, 26 09:59 AM
 Delaware & Hudson Railway—Wurts brothers canal 1823, gravity railroad 1829, Stourbridge Lion, Bridge Line to Montreal. Guilford 1984, CP 1991, NS south line 2015, CPKC north.
-
Delaware & Hudson Diesel Roster (All-Time)
Sep 15, 26 12:17 AM
 All-time Delaware & Hudson diesel roster—Alco S-2s through C-628s and PA-4s, GE U-boats, Baldwin RF-16s, EMD SD45s and GP38-2/GP39-2s. Serials, dates, dispositions.
-
Granite Railway, Our Country's First Railroad
Sep 14, 26 11:28 PM
 Granite Railway of Quincy, Massachusetts—chartered March 4, 1826, opened October 7, 1826. Gridley Bryant, 5-foot gauge, horses, Bunker Hill Monument stone. First commercial U.S. railroad.
-
Milwaukee Road Skytop Lounges: History, Specs & Floor Plans
Sep 14, 26 11:09 PM
 Milwaukee Road Skytop observation cars—Brooks Stevens, 1948. Four Rapids parlor-lounges from Milwaukee Shops, six Creek sleeper-lounges from Pullman-Standard. Floor plans, roster, preservation.
-
West Virginia Christmas Train Rides (2026): A Complete Guide
Sep 14, 26 11:02 PM
2026 West Virginia Christmas trains—Potomac Eagle North Pole Express in Romney and Christmas at Cass. Not Polar Express. Elkins Polar is not listed for 2026. -
Railroads Of Today: Class I Map, PSR & the 2026 Industry
Sep 14, 26 10:30 PM
 U.S. freight rail in 2026—six Class I railroads on a nearly 140,000-mile network. PSR as everyday practice, how the STB works, traffic mix, short lines and regionals.
-
Railroad History (USA): Timeline, Facts & How the Network Was Built
Sep 14, 26 10:03 PM
 Full U.S. railroad history hub—origins and inventors, Golden Age peak mileage, Civil War and transcontinental, streamliners, ICC regulation, Penn Central and Conrail, Staggers Act, PSR, and today’s Cl…
-
Railroads In The 2020s: CPKC, East Palestine & the UP–NS Case
Sep 14, 26 09:51 PM
 U.S. railroads 2020–2026—Class I mileage 91,773 in 2020. COVID traffic drop, CPKC April 14 2023, East Palestine Feb. 3 2023, UP–NS $85 billion case still before the STB.
-
Railroads In The 2010s: PSR, Coal’s Decline & Positive Train Control
Sep 14, 26 03:51 PM
 U.S. railroads 2010–2020—Class I mileage 95,573 to 91,773. Buffett closed BNSF Feb. 12 2010, Harrison at CP June 29 2012 and CSX 2017, PTC deadline Dec. 31 2018.
-
Virginia Christmas Train Rides (2026): A Complete Guide
Sep 14, 26 03:46 PM
 2026 Virginia Christmas trains—Virginia Scenic Railway Santa Express from Staunton, about 60 minutes. Confirm dates. Not Polar Express.
-
MARC Train: Maryland Commuter Rail History, Lines & Roster
Sep 14, 26 01:16 PM
 MARC Train history—Maryland Rail Commuter 1984, B&O and PRR corridors, Penn/Camden/Brunswick lines, Silver Spring 1996, all-time locomotive roster.
-
Railroads In The 2000s: Merger Freeze, Wisconsin Central & Buffett
Sep 13, 26 07:57 AM
 U.S. railroads 2000–2010—Class I mileage 99,250 to 95,573. STB merger freeze March 17 2000, CN–WC Oct. 9 2001, BNSF Railway Jan. 24 2005, Buffett Nov. 3 2009.
-
Railroads In The 1990s: Mega-Mergers, Conrail’s Split & the STB
Sep 13, 26 12:13 AM
 U.S. railroads 1990–2000—Class I mileage 119,758 to 99,250. BNSF Sept. 22 1995, UP–SP Sept. 11 1996, Conrail split June 1 1999, ICC Termination Dec. 29 1995.
-
Railroads In The 1980s: Staggers, Mega-Mergers & Conrail’s IPO
Sep 12, 26 11:12 PM
 U.S. railroads 1980–1990—Class I mileage 164,822 to 119,758. Staggers Oct. 14 1980, CSX and Norfolk Southern, UP–Missouri Pacific–Western Pacific, Conrail IPO March 26 1987.
-
Wabash Class O-1 4-8-4s: History, Roster & Specifications
Sep 12, 26 11:01 PM
 Wabash Class O-1 4-8-4s—Baldwin 1930–31, twenty-five engines 2900–2924. Fast freight, complete roster, specifications. None preserved.
-
Staggers Rail Act of 1980: Statute, Contract Rates & the ICC
Sep 10, 26 11:23 PM
 Staggers Rail Act, Pub. L. 96-448, signed October 14, 1980. Harley Staggers, S.1946, contract rates, 180% variable-cost test, abandonments, short lines.
-
Rock Island E8A 652: Bicentennial Independence Paint & History
Sep 10, 26 10:42 PM
 Rock Island E8A 652—EMD March 1952, serial 15199. 20th Century Railroad Club Independence bicentennial scheme, Peoria and Quad Cities Rockets, Midland Railway, Manly Junction Museum.
-
Vermont Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 10:37 PM
2026 Vermont Christmas trains—Okemo Valley Holiday Express from Chester Depot Dec. 19–20. Polar is Burlington Dec. 5–6 only. -
Railroads In The 1970s: Penn Central, Amtrak & Conrail
Sep 10, 26 10:18 AM
 U.S. railroads 1970–1980—196,479 miles at the decade’s start. Penn Central bankruptcy June 21 1970, Amtrak May 1 1971, 3R/4R Acts, Conrail April 1 1976, Rock Island 1975, Milwaukee 1977.
-
Railroads In The 1960s: Mergers, Passenger Collapse & Penn Central
Sep 10, 26 10:03 AM
 U.S. railroads 1960–1970—207,334 to 196,479 miles. Erie Lackawanna 1960, C&O–B&O 1963, N&W–Nickel Plate 1964, SCL 1967, Penn Central Feb. 1 1968.
-
South Carolina Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 08:36 AM
 2026 South Carolina Christmas trains—South Carolina Railroad Museum Santa Train in Winnsboro. Confirm December dates. Not Polar Express. Drop light-festival padding.
-
Steam Locomotive Feedwater Heaters: Elesco, Coffin & Worthington
Sep 10, 26 08:29 AM
 Steam locomotive feedwater heaters—open Worthington vs closed Elesco and Coffin. How they work, how to identify them on a smokebox, and why not every engine had one.
-
Oregon Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 08:22 AM
2026 Oregon Christmas trains—Portland Holiday Express, Garibaldi Candy Cane Express, Sumpter Valley Christmas Trains Dec. 11–13. Polar is Mount Hood. -
Lake Shore & Michigan Southern: Map, History, Timetables
Sep 10, 26 08:12 AM
 Lake Shore & Michigan Southern Railway—Erie & Kalamazoo 1833, Michigan Southern to Chicago 1852, LS&MS April 6 1869, Vanderbilt, Ashtabula 1876, NYC merger Dec. 22 1914. 1910 map and Official Guide.
-
Big Four Route (CCC&StL): Map, History
Sep 10, 26 12:19 AM
Cleveland, Cincinnati, Chicago & St. Louis Railway—Bee Line 1868, Ingalls’s first Big Four 1880, CCC&StL June 30, 1889, NYC lease Feb. 1, 1930. 1910 and 1930 maps, what still runs. -
Railroads In The 1950s: Diesel, the Interstate & Passenger Collapse
Sep 10, 26 12:15 AM
 U.S. railroads 1950–1960—223,779 to 211,459 miles. Interstate June 29, 1956, dieselization, passenger collapse, TOFC, 1957–58 recession, NYO&W 1957, N&W–Virginian 1959.
-
New Jersey Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 12:06 AM
 2026 New Jersey Christmas trains—Black River & Western Santa Express from Flemington and Pine Creek Christmas trains in Wall Township. Polar is Whippany and Phillipsburg.
-
New Mexico Christmas Train Rides (2026): A Complete Guide
Sep 09, 26 11:57 PM
 2026 New Mexico Christmas trains—Cumbres & Toltec Santa’s Holiday Express from Chama Dec. 5–6 (and Antonito, Colo., Dec. 12–13). Coach $25/$15. Not Polar Express.
-
Grand Trunk Railway: Map, History, Timetables
Sep 09, 26 11:47 PM
 Grand Trunk Railway of Canada—charter Nov. 10, 1852, Montreal–Toronto 1856, Portland, Sarnia, Victoria Bridge, St. Clair Tunnel 1891, Great Western 1882, GTPR, CN Jan. 20, 1923. 1893 map and Official…
-
Troop Trains In World War II: Sleepers, Kitchen Cars & Movements
Sep 09, 26 11:42 PM
 WWII U.S. troop trains—almost 44 million armed-services passengers, Pullman troop sleepers, ACF kitchen cars, hospital trains, monthly movement tables 1942–45. Not the Military Railway Service. ODT an…
-
Railroads In The 1940s: War Traffic, Last Steam & the Diesel Flood
Sep 09, 26 11:37 PM
 U.S. railroads 1940–1950—233,670 to 223,779 miles. World War II as the decade’s center, last new steam, diesel flood after V-J Day, 1945 car orders, California Zephyr 1949.
-
Railroads In World War II: ODT, Record Traffic & Private Operation
Sep 09, 26 03:00 PM
 U.S. railroads in World War II—Lend-Lease freight, Pearl Harbor, Office of Defense Transportation, 1944 peak ~740 billion ton-miles, Dec. 1943–Jan. 1944 seizure. Private operation, not a USRA sequel.
-
Montana Christmas Train Rides (2026): A Complete Guide
Sep 09, 26 02:54 PM
2026 Montana Christmas trains—Charlie Russell Chew Choo North Pole Adventure from Hanover/Lewistown, Nov. 27–Dec. 19, $71, about 1.5 hours. Not Polar Express. -
Railroads In The 1930s: Depression, Streamliners & the FT
Sep 09, 26 09:32 AM
 U.S. railroads 1930–1940—249,052 to 233,670 miles. Section 77, Eastman, Motor Carrier Act, M-10000 and Pioneer Zephyr 1934, EMC FT 1939. Decade frame, not the streamliner encyclopedia.
-
Sugar Cane Train (Lahaina): LK&P History, Roster & 2026 End
Sep 09, 26 08:19 AM
 Lahaina, Kaanapali & Pacific Sugar Cane Train—3-foot tourist line 1970–2014. Anaka, Myrtle, 2023 and 2025 fires, September 2026 scrapping. Roster, Hahakea trestle, Pioneer Mill corridor.
-
Massachusetts Christmas Train Rides (2026): A Complete Guide
Sep 09, 26 08:16 AM
 2026 Massachusetts Christmas trains—Shelburne Falls Moonlight Magic Friday Nov. 27; Edaville Festival of Lights in Carver. Polar is Cape Cod Central in Buzzards Bay.