Railroads In The 1990s: Mega-Mergers, Conrail’s Split & the STB
Published: September 13, 2026
By: Adam Burns
The 1990s opened with a Class I map the 1980s had already redrawn and closed with one the present tense still uses. Class I miles of road stood at 119,758 in 1990 and 99,250 in 2000—the same Association of American Railroads series that put 164,822 miles on the books in 1980. Ton-miles went the other way, from 1,033,969 million to 1,465,960 million. Burlington Northern and Santa Fe became one holding company on September 22, 1995. Union Pacific took the Chicago & North Western that year and Southern Pacific on September 11, 1996. Congress abolished the Interstate Commerce Commission on December 29, 1995; the Surface Transportation Board opened New Year’s Day. Norfolk Southern and CSX split Conrail on June 1, 1999. Canadian National took the Illinois Central that July.
The 1980s—Staggers, CSX, Norfolk Southern, Union Pacific–Missouri Pacific–Western Pacific, the Conrail IPO, the merger the ICC stopped—are that decade. The statute itself is Staggers. What follows here is 1990 through 2000: the western combinations the 1980s had left unfinished, an eastern freight railroad divided instead of sold whole, a new federal board in place of the Commission, and a Class I plant that kept shrinking while the ton-miles climbed.
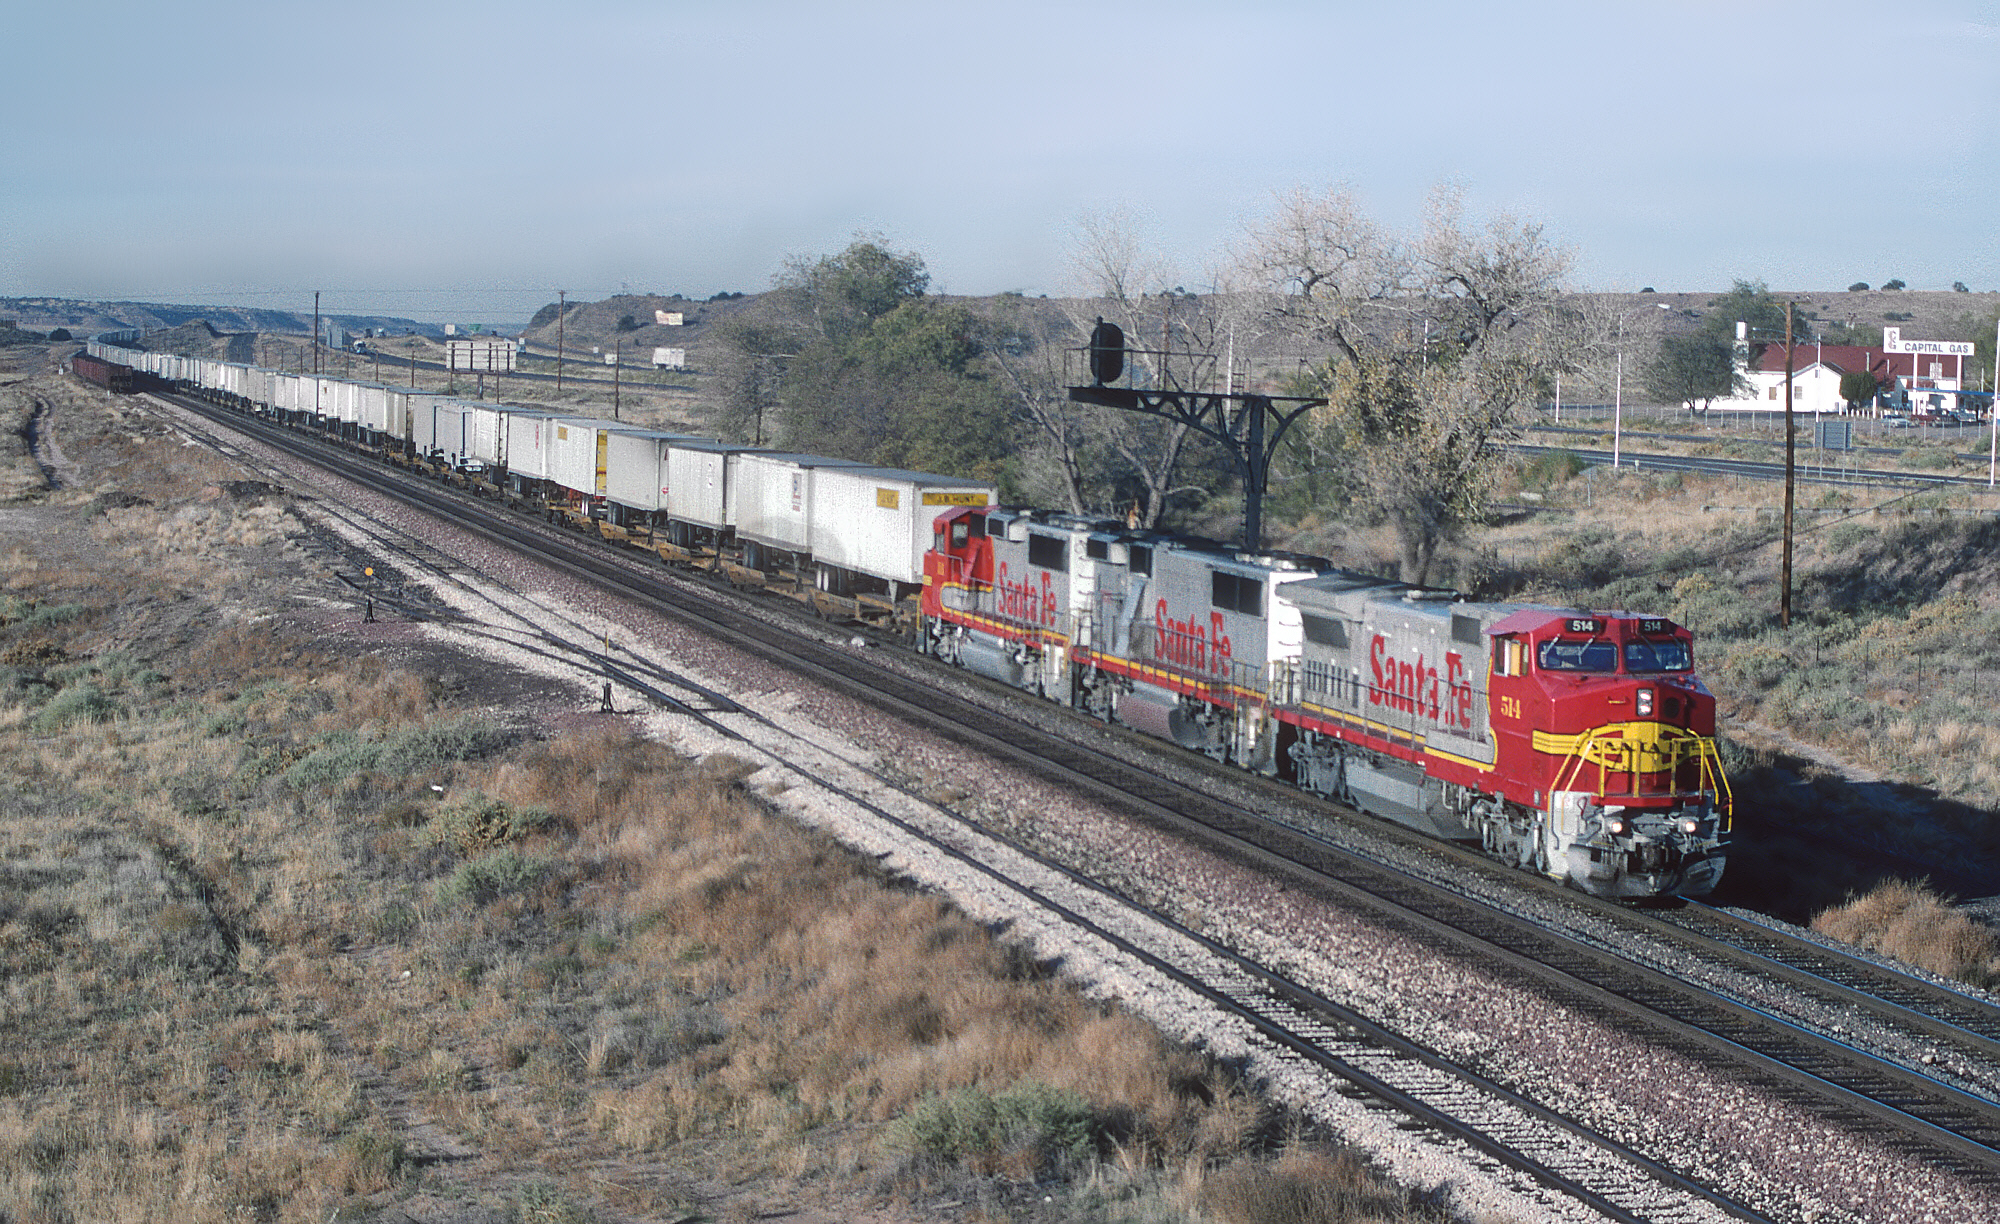
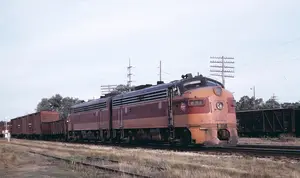
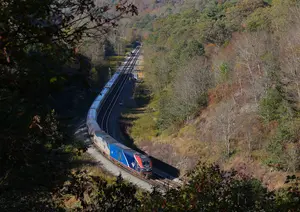
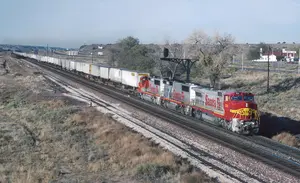
Santa Fe B40-8W 514 at Saunders, Arizona (the railroad called it Cheto), on October 29, 1994. Marty Bernard photo.
On this page: At a glance · The map of 1990 · Burlington Northern and Santa Fe · Union Pacific, the North Western, and Southern Pacific · The Conrail split · Canadian National and the Illinois Central · From the ICC to the STB · Miles down, ton-miles up · Into the 2000s
At a glance
| Item | Detail |
|---|---|
| Class I miles of road, 1990 | 119,758 (AAR / BTS series; same series as 164,822 in 1980 on the 1980s page) |
| Class I miles of road, 1995 | 108,264 |
| Class I miles of road, 2000 | 99,250 |
| Class I ton-miles, 1990 | 1,033,969 million |
| Class I ton-miles, 1995 | 1,305,688 million |
| Class I ton-miles, 2000 | 1,465,960 million |
| Norfolk Southern Railway | Operating merger, N&W into Southern, December 31, 1990. Holding company was 1982 |
| NAFTA | In force January 1, 1994. North–south freight context, not a statute dump |
| BN–Santa Fe announced | June 30, 1994 |
| Union Pacific control of C&NW | ICC common-control March 7, 1995, effective April 6. $1.2 billion purchase treated as completed June 24, 1995 |
| BNSF holding company | Consummated September 22, 1995, 8:32 a.m. EDT. ICC 4–0 July 20; written decision August 23 |
| ICC Termination Act | Pub. L. 104-88, signed December 29, 1995. Surface Transportation Board from January 1, 1996 |
| BN and Santa Fe operating merger | December 31, 1996, as Burlington Northern and Santa Fe Railway |
| Union Pacific–Southern Pacific | STB 3–0 July 3, 1996, $5.4 billion. Consummated September 11, 1996, 10 a.m. CT |
| Houston / Texas service crisis | Summer–fall 1997, after the SP integration |
| CSX / NS Conrail transaction | Agreement June 10, 1997. STB vote June 8, 1998; Decision No. 89 July 23 |
| Conrail Control Date | August 22, 1998 |
| Conrail Split Date / Day One | June 1, 1999. NS about 58 percent of the routes, CSX about 42. Shared Assets in North Jersey, South Jersey/Philadelphia, and Detroit |
| CN–Illinois Central | STB vote March 25, 1999; written decision May 25. Integration July 1, 1999 |
| Not this decade | BNSF Railway name (January 24, 2005). CN–Wisconsin Central (2001). Buffett / BNSF (2009). PSR as a brand. CPKC. The 2026 Class I map |
Class I mileage and ton-miles from Association of American Railroads, Railroad Facts, as tabulated by the Bureau of Transportation Statistics. Information compiled September 12, 2026.
The map of 1990
On the last day of 1990 Norfolk Southern became one operating railroad: Southern took the Norfolk & Western and changed its name. The holding company had been June 1, 1982. CSX Transportation had already absorbed the Chessie names. Union Pacific controlled Missouri Pacific and Western Pacific. Conrail was a public company, three years past its IPO. Southern Pacific belonged to Philip Anschutz and Rio Grande Industries. Santa Fe was still Santa Fe. Soo Line was digesting Milwaukee Road. Kansas City Southern was still the north–south independent. Class I mileage was under 120,000. Ton-miles were over a trillion.
That is what the 1980s left on the table. Staggers was ten years old and already a working tool: confidential contracts, faster line sales, an ICC that no longer suspended every increase and had already said no to Santa Fe–Southern Pacific in 1986. Canadian Pacific took the Delaware & Hudson out of Guilford’s bankruptcy in January 1991. Wisconsin Central, spun from Soo in 1987, spent the decade as a Midwestern regional that flirted with the old Class I revenue line. Those company stories stay on their pages. The 1990s assignment was to finish the western map, divide the Northeast, and replace the Commission.
Burlington Northern and Santa Fe
Burlington Northern and the Atchison, Topeka & Santa Fe announced a combination on June 30, 1994. Shareholders approved it on February 7, 1995. The ICC voted 4–0 on July 20, 1995 and issued the written decision on August 23. The holding company—Burlington Northern Santa Fe Corporation—was consummated at 8:32 a.m. EDT on September 22, 1995. The two operating railroads merged on December 31, 1996, as the Burlington Northern and Santa Fe Railway. The later short name, BNSF Railway, is January 24, 2005. The company encyclopedia is BNSF. Burlington Northern’s own history is that page; Santa Fe’s is Santa Fe.
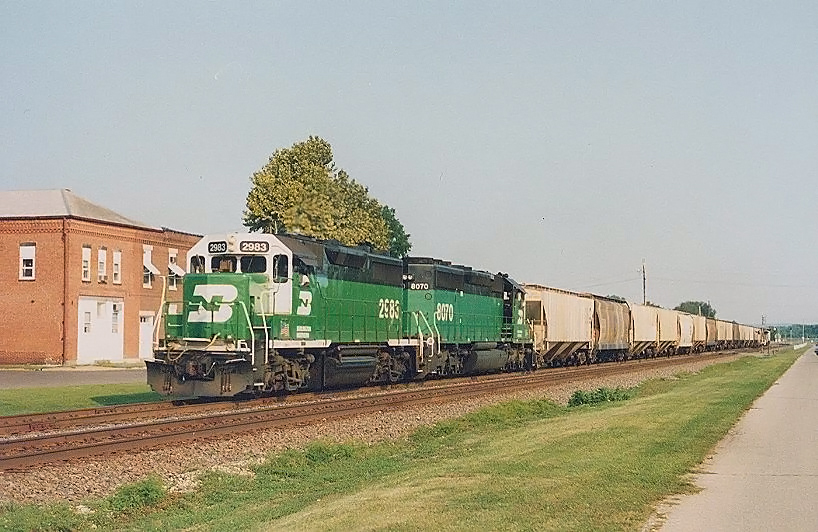
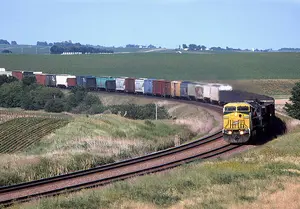
Burlington Northern GP35m 2983 and SD40-2 8070 westbound with a short local at Cassville, Wisconsin, along the Mississippi River on August 24, 1991. Doug Kroll photo.
Cassville is still Burlington Northern, four years before the announcement: a Mississippi River local on the old Chicago, Burlington & Quincy. The Arizona photograph is still Santa Fe, four months after the announcement: a Super Fleet B40-8W in warbonnet paint at a timetable location the railroad called Cheto. The ICC had stopped Santa Fe and Southern Pacific in 1986. This combination was end-to-end enough to pass—Powder River and the Pacific Northwest on one side, Chicago–California and the Southwest on the other—with conditions. The 2009 Berkshire Hathaway purchase is not this decade.
Union Pacific, the North Western, and Southern Pacific
Union Pacific already reached Chicago and the Bay Area from the 1982 control of Missouri Pacific and Western Pacific. The Chicago & North Western was the next piece. The ICC approved common control on March 7, 1995, effective April 6. A cash tender at $35 a share ran in March. The New York Times treated the $1.2 billion purchase as completed on June 24, 1995, after 99.5 percent of the shares; the Commission’s reasonableness ruling was June 23. The North Western encyclopedia is Chicago & North Western. Union Pacific is Union Pacific.
Southern Pacific was the larger unfinished business. Santa Fe Southern Pacific had been denied in 1986; Anschutz had bought SP in 1988. Union Pacific announced the Southern Pacific on August 3, 1995. The new Surface Transportation Board voted 3–0 on July 3, 1996, a $5.4 billion transaction, and issued the written decision on August 6. Control was consummated at 10 a.m. Central Time on September 11, 1996, effective October 1. The SP encyclopedia is Southern Pacific.
The integration did not go quietly. Through the summer and fall of 1997 the Houston and Texas Gulf terminal area seized up—cars lost, crews out of place, chemical and grain shippers filing at the Board. Fred Frailey later called it the mother of all coagulations. Emergency service orders followed. Missouri Pacific, still a paper railroad after 1982, was merged into Union Pacific Railroad on January 1, 1997. The 1996–97 map was yellow paint on more miles than the operating department could digest at once. That is the 1990s fact. Precision Scheduled Railroading is later than that.
The Conrail split
Conrail had been a listed freight railroad since March 26, 1987. Restrictions from the privatization kept another Class I from buying it on the spot. CSX announced an agreement to acquire it on October 15, 1996. Norfolk Southern bid against that agreement. The two eastern companies settled on a division: a Transaction Agreement on June 10, 1997, and a joint application on June 23. The STB voted on June 8, 1998 and issued Decision No. 89 on July 23. Control Date was August 22, 1998. Split Date—Day One, when the allocated routes changed hands—was June 1, 1999.
Norfolk Southern took about 58 percent of Conrail’s routes, including the old New York Central west of Cleveland and much of the Pennsylvania’s former main. CSX took about 42 percent, including the New York Central east of Cleveland and much of the former New York Central / Boston & Albany toward New England. Three Shared Assets Areas—North Jersey, South Jersey/Philadelphia, and Detroit—stayed in a Conrail residual so both buyers could reach the same terminals. The company encyclopedia is Conrail. CSX is CSX; Norfolk Southern is Norfolk Southern.
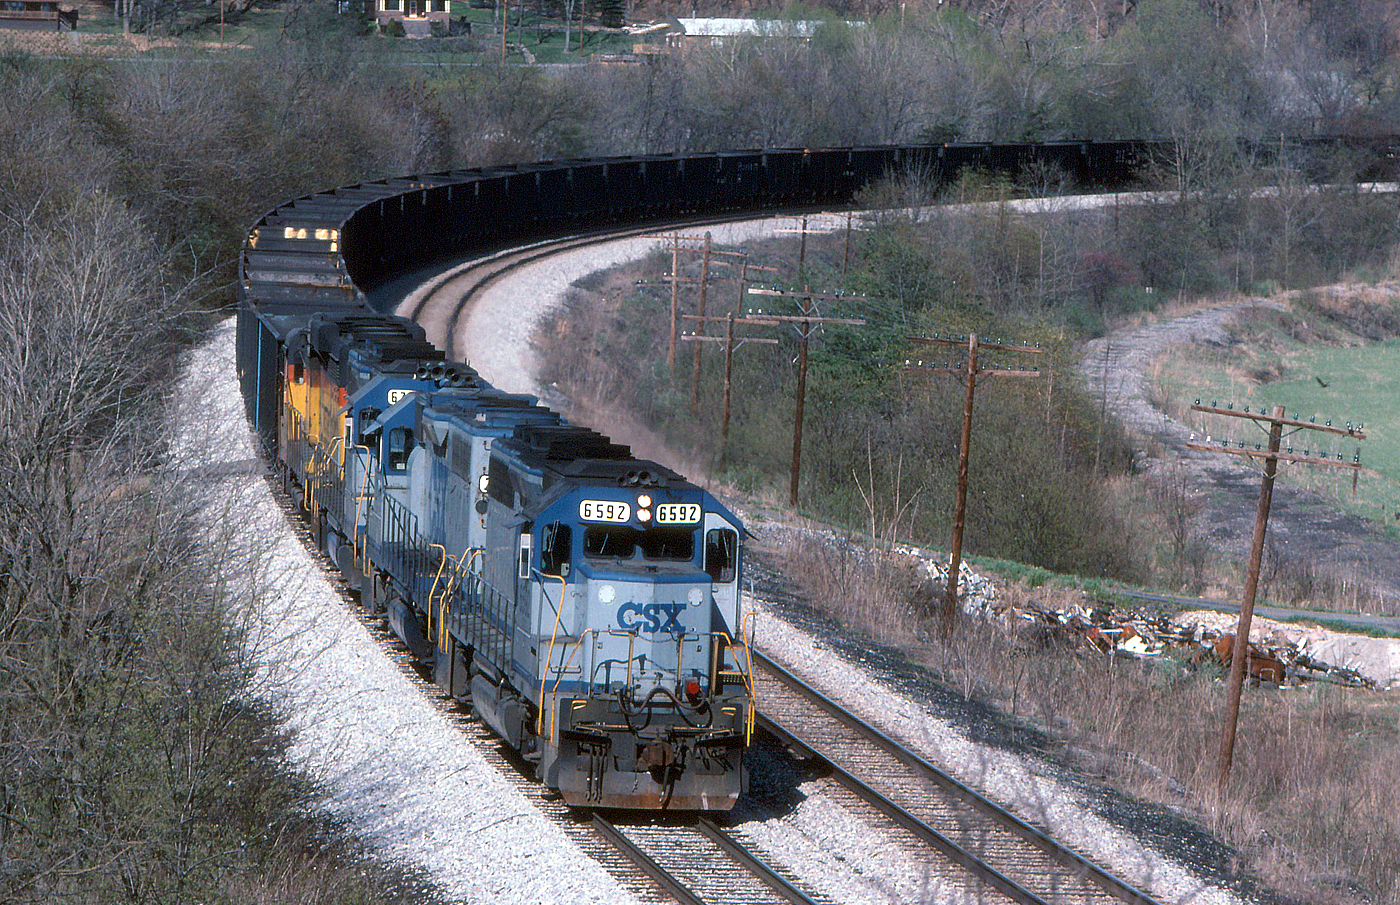
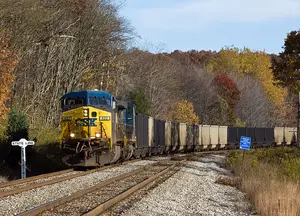
Four CSX Geeps, GP40 6592 leading, with empty coal train B875 through Pinto, Maryland, bound for a mine on the former Western Maryland Thomas Sub. Twenty years earlier this train would have been on WM rails here; the abandoned WM right-of-way is at right. April 17, 1994. Wade Massie photo.
Pinto is the 1980s eastern map already at work, five years before anyone divided Conrail. CSX Transportation was running the former Baltimore & Ohio. The Western Maryland had gone into the B&O on May 1, 1983; its Thomas Sub toward the West Virginia mines is the assignment, and the abandoned parallel is in the photograph. The WM encyclopedia is Western Maryland. Train B875 is 1990s CSX coal on someone else’s former railroad. The 1999 split gave CSX and Norfolk Southern the Conrail plant the same way.
Canadian National and the Illinois Central
Canadian National announced the Illinois Central on February 10, 1998, about $2.4 billion. The application went to the STB on July 15 as Finance Docket 33556. The Board voted on March 25, 1999 and issued the written decision on May 25. Integration was July 1, 1999. It was an end-to-end Chicago–New Orleans franchise hung under CN’s existing Chicago access, not a parallel merger. Kansas City Southern argued that IC’s Alliance/Access arrangements made the deal three-handed; the Board did not treat it that way. KCS stayed independent. The IC encyclopedia is Illinois Central. Canadian National is Canadian National. Kansas City Southern is Kansas City Southern.
Hunter Harrison was already running Illinois Central to a schedule in the 1990s. That is a date on this page. The later Precision Scheduled Railroading brand is not. NAFTA had been in force since January 1, 1994; north–south carloads were part of the argument for CN–IC and for KCS’s own Mexican franchise. Wisconsin Central, still independent, would go to CN in 2001. Soo Line remained a Canadian Pacific subsidiary. Those later combinations are the next decade and today.
From the ICC to the STB
The Interstate Commerce Commission had opened in 1887. Staggers had taken it out of most rates in 1980 and left it in mergers, abandonments, and captive-shipper cases. Congress finished the agency in the ICC Termination Act, H.R. 2539, Public Law 104-88, signed December 29, 1995. The Surface Transportation Board opened January 1, 1996. The 180-percent revenue-to-variable-cost test and the market-dominance inquiry came with it. The statute encyclopedia for 1980 remains Staggers. This page is the date the Commission died and the Board heard the rest of the decade’s mergers.
Union Pacific–Southern Pacific was the Board’s first large railroad combination. Conrail and CN–IC followed. The ICC had still been the forum for BN–Santa Fe and UP–North Western. One decade, two agencies, the same Staggers cage. How the STB works in 2026 is the today page.
Miles down, ton-miles up
Class I miles of road fell from 119,758 (1990) to 108,264 (1995) to 99,250 (2000). A large part of the drop is still sales. The AAR counted several hundred non-Class I railroads on the order of 40,000 miles by the mid-1990s. Wisconsin Central, New England Central (the old Central Vermont, 1995), and the rest of the Staggers spinoff crop are short lines and regionals. Stover’s older first-track series on the pre-1960 decade pages is a different column. The today page uses 164,822 (1980) and 136,650 (2020) for a national-network snapshot. Direction is the same: a smaller Class I plant carrying more freight.
Class I ton-miles rose from 1,033,969 million in 1990 to 1,305,688 million in 1995 to 1,465,960 million in 2000. Powder River coal, stack trains, and contract grain filled longer consists. AC traction arrived as a working locomotive, not a test: Burlington Northern’s SD70MACs in 1993, GE’s AC4400CW behind them. Santa Fe’s Super Fleet Dash 8s, the Arizona photograph, were the wide-cab generation already on the point. That hardware story is diesel locomotives.
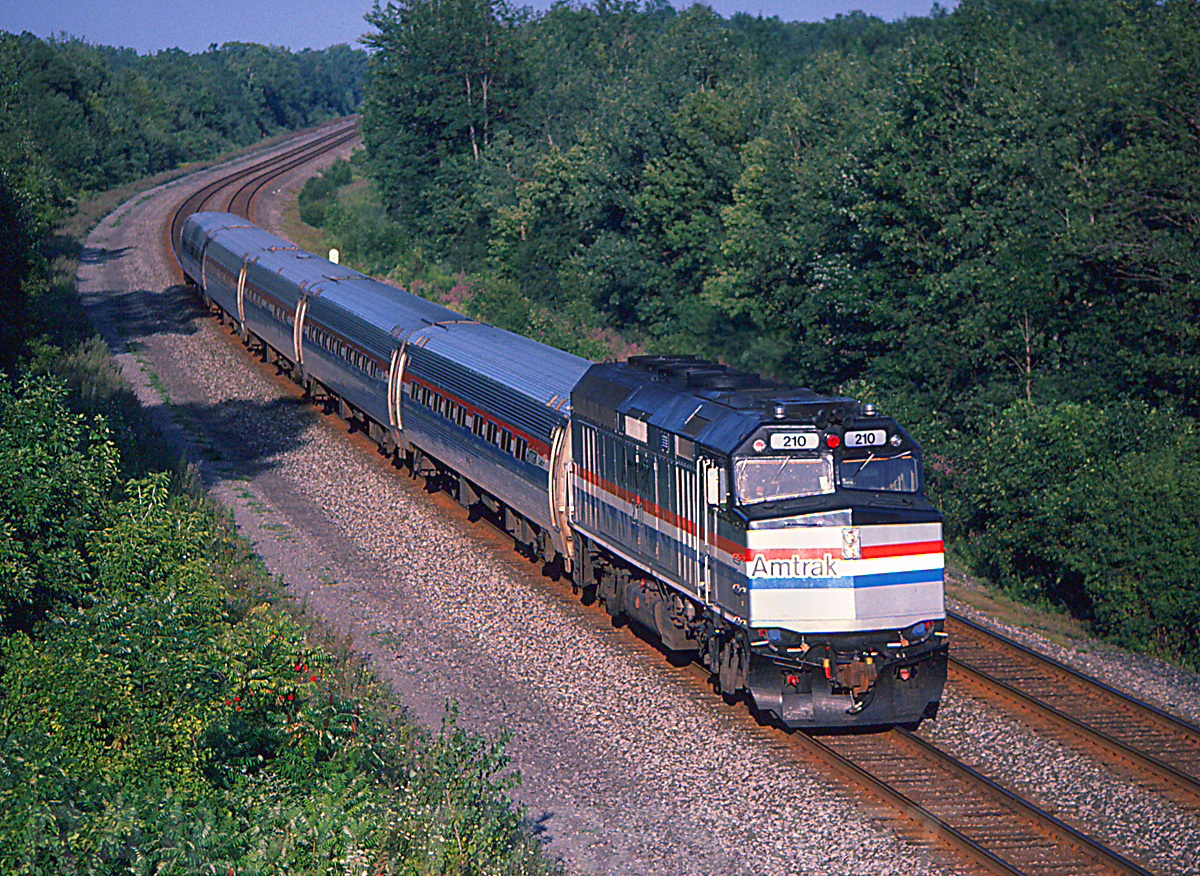
Amtrak F40PH 283 with train 210 at Memphis, New York, on August 13, 1993. Wade Massie photo.
Memphis is a hamlet west of Syracuse on the Empire Corridor, not the Tennessee city. W. Graham Claytor Jr.’s Amtrak presidency ran through 1993. Metrolink opened in Southern California on October 26, 1992. Amtrak ordered the Acela trainsets in 1996; first revenue service is December 11, 2000. The passenger encyclopedias are Amtrak and commuter rail.
Into the 2000s
By 2000 the western duopoly was in place: BNSF and a Union Pacific that now included the North Western and Southern Pacific. CSX and Norfolk Southern had divided Conrail. Canadian National had the Illinois Central. The ICC was gone. Class I mileage was under 100,000. Ton-miles were approaching a trillion and a half. Kansas City Southern was still independent. Wisconsin Central was still independent. Soo was still Canadian Pacific.
Canadian National and Wisconsin Central (2001), the BNSF Railway name (January 24, 2005), Berkshire Hathaway’s purchase of BNSF (2009), Precision Scheduled Railroading as a brand, Canadian Pacific Kansas City, and the pending Union Pacific–Norfolk Southern case are later than this page. The present-tense industry—who the Class Is are, how the STB works, what the 2026 map looks like—is railroads of today. The 1990s left them two western systems, two eastern systems, a Canadian north–south on the Illinois Central, a federal board instead of the Commission, and a short-line industry still standing on the miles the Class Is no longer wanted.
Related reading on American-Rails.com
- Railroad History (USA) · Railroads In The 1980s · Staggers Act · Railroads of today
- Class I railroads · BNSF · Burlington Northern · Santa Fe
- Union Pacific · Chicago & North Western · Southern Pacific
- CSX · Norfolk Southern · Conrail · Illinois Central
- Canadian National · Canadian Pacific · Kansas City Southern
- Short lines · Regionals · Commuter rail · Amtrak
Sources
- Association of American Railroads, Railroad Facts, Class I miles of road and ton-miles, as tabulated by the Bureau of Transportation Statistics (119,758 / 1,033,969 million in 1990; 108,264 / 1,305,688 million in 1995; 99,250 / 1,465,960 million in 2000)
- Burlington Northern–Santa Fe: announced June 30, 1994; ICC Finance Docket 32549, vote July 20, 1995 (4–0), written decision August 23, 1995; holding-company consummation September 22, 1995, 8:32 a.m. EDT; operating railroads merged December 31, 1996. Live American-Rails BNSF and Burlington Northern pages
- Union Pacific–Chicago & North Western: ICC common-control March 7, 1995, effective April 6; $35-a-share tender; New York Times, June 24, 1995 ($1.2 billion, 99.5 percent of shares); ICC reasonableness ruling June 23, 1995
- Union Pacific–Southern Pacific: announced August 3, 1995; STB vote July 3, 1996 (3–0), $5.4 billion, written decision August 6; consummated September 11, 1996, 10 a.m. CT, effective October 1, 1996. Houston / Texas Gulf service crisis, summer–fall 1997 (Fred W. Frailey, Trains)
- Missouri Pacific merged into Union Pacific Railroad, January 1, 1997
- ICC Termination Act, H.R. 2539, Pub. L. 104-88, signed December 29, 1995; Surface Transportation Board from January 1, 1996
- CSX / Norfolk Southern–Conrail: CSX agreement announced October 15, 1996; Transaction Agreement June 10, 1997; joint application June 23, 1997; STB vote June 8, 1998; Decision No. 89 July 23, 1998; Control Date August 22, 1998; Split Date / Day One June 1, 1999. NS about 58 percent of routes, CSX about 42; Shared Assets Areas North Jersey, South Jersey/Philadelphia, Detroit
- Canadian National–Illinois Central: announced February 10, 1998, about $2.4 billion (Washington Post, Chicago Tribune, New York Times, February 11, 1998); STB Finance Docket 33556, application July 15, 1998; vote March 25, 1999; written decision May 25, 1999; integration July 1, 1999. Railway Gazette effective date June 24, 1999
- North American Free Trade Agreement, in force January 1, 1994. Canadian Pacific purchase of Delaware & Hudson, January 1991. Metrolink, October 26, 1992. Western Maryland into Baltimore & Ohio, May 1, 1983
- Norfolk Southern operating merger, December 31, 1990 (holding company June 1, 1982), on the 1980s page. Short-line mileage order of magnitude from the Staggers rewrite (AAR / mid-1990s non-Class I count)
Recent Articles


-
Bessemer & Lake Erie Railroad: "The Bessemer Road"
Sep 15, 26 05:20 PM
 Bessemer & Lake Erie—Bear Creek 1865, Carnegie 1897, U.S. Steel 1901. Ore south from Conneaut, coal north. 2-10-4s, Missabe sister road. CN May 10, 2004. Complete corporate history.
-
Bangor and Aroostook Railroad: "Serving Northern Maine"
Sep 15, 26 05:05 PM
 Bangor & Aroostook—chartered February 13, 1891, first trains January 1, 1894. Potatoes, paper, Searsport, State of Maine reefers. MM&A 2003, Lac-Mégantic 2013, CP 2020, CPKC today. Complete co…
-
Baltimore & Ohio Chicago Terminal Railroad: Map and History
Sep 15, 26 03:11 PM
 B&OCT—formed January 6, 1910 to buy Chicago Terminal Transfer. Grand Central, Barr Yard, 78 route-miles. Assigned B&O steam. Complete diesel roster. CSX paper subsidiary, mark BOCT.
-
The "Alphabet Route" (Railroad): Photos and History
Sep 15, 26 02:53 PM
 Alphabet Route—eight railroads, not one company. P&WV to Connellsville February 11, 1931. Alpha Jets Chicago/St. Louis–New York/Boston. NKP, W&LE, P&WV, WM, Reading, CNJ, L&HR, New Hav…
-
Milwaukee Road Livestock Operations: Cattle, Dakotas & Montana
Sep 15, 26 02:36 PM
 Milwaukee Road livestock traffic—Dakota and Montana cattle, Iowa hogs, Chicago markets, 28-hour law, head-end stock cars. By 1974 mostly Montana. Rick Burn’s Helena speech. Operations history, not the…
-
Spirit of Jasper Ride & Dine (2026): Season Pause
Sep 15, 26 02:29 PM
 Spirit of Jasper Ride & Dine in Jasper, Indiana—seated meal on board. Operator: not running public trains for 2026. Depot remains open as a rental. Confirm on spiritofjaspertrain.com.
-
South Carolina Canal & Rail Road Company: Map and History
Sep 15, 26 01:59 PM
 South Carolina Canal & Rail Road—chartered December 19, 1827. Best Friend of Charleston, 136 miles Charleston–Hamburg October 1833, Aiken inclined plane. South Carolina Railroad 1844, Southern 189…
-
The Practice of Double-Heading: The Steam Era
Sep 15, 26 01:43 PM
 Doubleheading—two locomotives on the point, each with its own steam crew. Not a rear helper, not diesel MU. How it worked, PRR 1877, mountain grades, and what MU ended.
-
Mohawk and Hudson Railroad: Map, Pictures, Locomotives
Sep 15, 26 01:20 PM
 Mohawk & Hudson Railroad—New York’s first railroad, chartered April 17, 1826. DeWitt Clinton, inclined planes, Albany & Schenectady 1847, first New York Central May 17, 1853. Complete corporat…
-
Essex Clipper Dinner Train (2026): Dates, Tickets & What to Expect
Sep 15, 26 01:09 PM
 2026 Essex Clipper Dinner Train in Essex, CT—2.5 hours, four-course meal $129.99, 18+. Fall dates through Oct. 25. Confirm on essexsteamtrain.com.
-
Camden & Amboy Railroad: Map, History, Photos
Sep 15, 26 12:53 PM
 Camden & Amboy Railroad—chartered February 4, 1830. Joint Companies monopoly with the Delaware & Raritan Canal, John Bull, T-rail. United New Jersey 1872, PRR 999-year lease 1871. Complete corpora…
-
Cafe Lafayette Dinner Train (2026): Dates, Tickets & What to Expect
Sep 15, 26 12:47 PM
2026 Cafe Lafayette Dinner Train in North Woodstock, NH—2 hours, 20 miles, five-course meal from $125. May–October. Confirm on nhdinnertrain.com. -
Christmas Train Ride Locations (2026): A Complete Guide
Sep 15, 26 10:47 AM
 2026 Christmas train rides by state—Santa, North Pole Express, and holiday trains. Not Polar Express. State guides and product pages. Confirm dates on each railroad.
-
Baltimore & Ohio Railroad: Linking 13 Great States With The Nation
Sep 15, 26 10:22 AM
 Baltimore & Ohio Railroad—first U.S. common carrier, chartered February 28, 1827. Wheeling 1853, Chicago 1874, C&O control 1963, Chessie 1973, into CSX April 30, 1987. Complete corporate history.
-
Delaware & Hudson Railway: The Bridge Line
Sep 15, 26 09:59 AM
 Delaware & Hudson Railway—Wurts brothers canal 1823, gravity railroad 1829, Stourbridge Lion, Bridge Line to Montreal. Guilford 1984, CP 1991, NS south line 2015, CPKC north.
-
Delaware & Hudson Diesel Roster (All-Time)
Sep 15, 26 12:17 AM
 All-time Delaware & Hudson diesel roster—Alco S-2s through C-628s and PA-4s, GE U-boats, Baldwin RF-16s, EMD SD45s and GP38-2/GP39-2s. Serials, dates, dispositions.
-
Granite Railway, Our Country's First Railroad
Sep 14, 26 11:28 PM
 Granite Railway of Quincy, Massachusetts—chartered March 4, 1826, opened October 7, 1826. Gridley Bryant, 5-foot gauge, horses, Bunker Hill Monument stone. First commercial U.S. railroad.
-
Milwaukee Road Skytop Lounges: History, Specs & Floor Plans
Sep 14, 26 11:09 PM
 Milwaukee Road Skytop observation cars—Brooks Stevens, 1948. Four Rapids parlor-lounges from Milwaukee Shops, six Creek sleeper-lounges from Pullman-Standard. Floor plans, roster, preservation.
-
West Virginia Christmas Train Rides (2026): A Complete Guide
Sep 14, 26 11:02 PM
2026 West Virginia Christmas trains—Potomac Eagle North Pole Express in Romney and Christmas at Cass. Not Polar Express. Elkins Polar is not listed for 2026. -
Railroads Of Today: Class I Map, PSR & the 2026 Industry
Sep 14, 26 10:30 PM
 U.S. freight rail in 2026—six Class I railroads on a nearly 140,000-mile network. PSR as everyday practice, how the STB works, traffic mix, short lines and regionals.
-
Railroad History (USA): Timeline, Facts & How the Network Was Built
Sep 14, 26 10:03 PM
 Full U.S. railroad history hub—origins and inventors, Golden Age peak mileage, Civil War and transcontinental, streamliners, ICC regulation, Penn Central and Conrail, Staggers Act, PSR, and today’s Cl…
-
Railroads In The 2020s: CPKC, East Palestine & the UP–NS Case
Sep 14, 26 09:51 PM
 U.S. railroads 2020–2026—Class I mileage 91,773 in 2020. COVID traffic drop, CPKC April 14 2023, East Palestine Feb. 3 2023, UP–NS $85 billion case still before the STB.
-
Railroads In The 2010s: PSR, Coal’s Decline & Positive Train Control
Sep 14, 26 03:51 PM
 U.S. railroads 2010–2020—Class I mileage 95,573 to 91,773. Buffett closed BNSF Feb. 12 2010, Harrison at CP June 29 2012 and CSX 2017, PTC deadline Dec. 31 2018.
-
Virginia Christmas Train Rides (2026): A Complete Guide
Sep 14, 26 03:46 PM
 2026 Virginia Christmas trains—Virginia Scenic Railway Santa Express from Staunton, about 60 minutes. Confirm dates. Not Polar Express.
-
MARC Train: Maryland Commuter Rail History, Lines & Roster
Sep 14, 26 01:16 PM
 MARC Train history—Maryland Rail Commuter 1984, B&O and PRR corridors, Penn/Camden/Brunswick lines, Silver Spring 1996, all-time locomotive roster.
-
Railroads In The 2000s: Merger Freeze, Wisconsin Central & Buffett
Sep 13, 26 07:57 AM
 U.S. railroads 2000–2010—Class I mileage 99,250 to 95,573. STB merger freeze March 17 2000, CN–WC Oct. 9 2001, BNSF Railway Jan. 24 2005, Buffett Nov. 3 2009.
-
Railroads In The 1990s: Mega-Mergers, Conrail’s Split & the STB
Sep 13, 26 12:13 AM
 U.S. railroads 1990–2000—Class I mileage 119,758 to 99,250. BNSF Sept. 22 1995, UP–SP Sept. 11 1996, Conrail split June 1 1999, ICC Termination Dec. 29 1995.
-
Railroads In The 1980s: Staggers, Mega-Mergers & Conrail’s IPO
Sep 12, 26 11:12 PM
 U.S. railroads 1980–1990—Class I mileage 164,822 to 119,758. Staggers Oct. 14 1980, CSX and Norfolk Southern, UP–Missouri Pacific–Western Pacific, Conrail IPO March 26 1987.
-
Wabash Class O-1 4-8-4s: History, Roster & Specifications
Sep 12, 26 11:01 PM
 Wabash Class O-1 4-8-4s—Baldwin 1930–31, twenty-five engines 2900–2924. Fast freight, complete roster, specifications. None preserved.
-
Staggers Rail Act of 1980: Statute, Contract Rates & the ICC
Sep 10, 26 11:23 PM
 Staggers Rail Act, Pub. L. 96-448, signed October 14, 1980. Harley Staggers, S.1946, contract rates, 180% variable-cost test, abandonments, short lines.
-
Rock Island E8A 652: Bicentennial Independence Paint & History
Sep 10, 26 10:42 PM
 Rock Island E8A 652—EMD March 1952, serial 15199. 20th Century Railroad Club Independence bicentennial scheme, Peoria and Quad Cities Rockets, Midland Railway, Manly Junction Museum.
-
Vermont Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 10:37 PM
2026 Vermont Christmas trains—Okemo Valley Holiday Express from Chester Depot Dec. 19–20. Polar is Burlington Dec. 5–6 only. -
Railroads In The 1970s: Penn Central, Amtrak & Conrail
Sep 10, 26 10:18 AM
 U.S. railroads 1970–1980—196,479 miles at the decade’s start. Penn Central bankruptcy June 21 1970, Amtrak May 1 1971, 3R/4R Acts, Conrail April 1 1976, Rock Island 1975, Milwaukee 1977.
-
Railroads In The 1960s: Mergers, Passenger Collapse & Penn Central
Sep 10, 26 10:03 AM
 U.S. railroads 1960–1970—207,334 to 196,479 miles. Erie Lackawanna 1960, C&O–B&O 1963, N&W–Nickel Plate 1964, SCL 1967, Penn Central Feb. 1 1968.
-
South Carolina Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 08:36 AM
 2026 South Carolina Christmas trains—South Carolina Railroad Museum Santa Train in Winnsboro. Confirm December dates. Not Polar Express. Drop light-festival padding.
-
Steam Locomotive Feedwater Heaters: Elesco, Coffin & Worthington
Sep 10, 26 08:29 AM
 Steam locomotive feedwater heaters—open Worthington vs closed Elesco and Coffin. How they work, how to identify them on a smokebox, and why not every engine had one.
-
Oregon Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 08:22 AM
2026 Oregon Christmas trains—Portland Holiday Express, Garibaldi Candy Cane Express, Sumpter Valley Christmas Trains Dec. 11–13. Polar is Mount Hood. -
Lake Shore & Michigan Southern: Map, History, Timetables
Sep 10, 26 08:12 AM
 Lake Shore & Michigan Southern Railway—Erie & Kalamazoo 1833, Michigan Southern to Chicago 1852, LS&MS April 6 1869, Vanderbilt, Ashtabula 1876, NYC merger Dec. 22 1914. 1910 map and Official Guide.
-
Big Four Route (CCC&StL): Map, History
Sep 10, 26 12:19 AM
Cleveland, Cincinnati, Chicago & St. Louis Railway—Bee Line 1868, Ingalls’s first Big Four 1880, CCC&StL June 30, 1889, NYC lease Feb. 1, 1930. 1910 and 1930 maps, what still runs. -
Railroads In The 1950s: Diesel, the Interstate & Passenger Collapse
Sep 10, 26 12:15 AM
 U.S. railroads 1950–1960—223,779 to 211,459 miles. Interstate June 29, 1956, dieselization, passenger collapse, TOFC, 1957–58 recession, NYO&W 1957, N&W–Virginian 1959.
-
New Jersey Christmas Train Rides (2026): A Complete Guide
Sep 10, 26 12:06 AM
 2026 New Jersey Christmas trains—Black River & Western Santa Express from Flemington and Pine Creek Christmas trains in Wall Township. Polar is Whippany and Phillipsburg.
-
New Mexico Christmas Train Rides (2026): A Complete Guide
Sep 09, 26 11:57 PM
 2026 New Mexico Christmas trains—Cumbres & Toltec Santa’s Holiday Express from Chama Dec. 5–6 (and Antonito, Colo., Dec. 12–13). Coach $25/$15. Not Polar Express.
-
Grand Trunk Railway: Map, History, Timetables
Sep 09, 26 11:47 PM
 Grand Trunk Railway of Canada—charter Nov. 10, 1852, Montreal–Toronto 1856, Portland, Sarnia, Victoria Bridge, St. Clair Tunnel 1891, Great Western 1882, GTPR, CN Jan. 20, 1923. 1893 map and Official…
-
Troop Trains In World War II: Sleepers, Kitchen Cars & Movements
Sep 09, 26 11:42 PM
 WWII U.S. troop trains—almost 44 million armed-services passengers, Pullman troop sleepers, ACF kitchen cars, hospital trains, monthly movement tables 1942–45. Not the Military Railway Service. ODT an…
-
Railroads In The 1940s: War Traffic, Last Steam & the Diesel Flood
Sep 09, 26 11:37 PM
 U.S. railroads 1940–1950—233,670 to 223,779 miles. World War II as the decade’s center, last new steam, diesel flood after V-J Day, 1945 car orders, California Zephyr 1949.
-
Railroads In World War II: ODT, Record Traffic & Private Operation
Sep 09, 26 03:00 PM
 U.S. railroads in World War II—Lend-Lease freight, Pearl Harbor, Office of Defense Transportation, 1944 peak ~740 billion ton-miles, Dec. 1943–Jan. 1944 seizure. Private operation, not a USRA sequel.
-
Montana Christmas Train Rides (2026): A Complete Guide
Sep 09, 26 02:54 PM
2026 Montana Christmas trains—Charlie Russell Chew Choo North Pole Adventure from Hanover/Lewistown, Nov. 27–Dec. 19, $71, about 1.5 hours. Not Polar Express. -
Railroads In The 1930s: Depression, Streamliners & the FT
Sep 09, 26 09:32 AM
 U.S. railroads 1930–1940—249,052 to 233,670 miles. Section 77, Eastman, Motor Carrier Act, M-10000 and Pioneer Zephyr 1934, EMC FT 1939. Decade frame, not the streamliner encyclopedia.
-
Sugar Cane Train (Lahaina): LK&P History, Roster & 2026 End
Sep 09, 26 08:19 AM
 Lahaina, Kaanapali & Pacific Sugar Cane Train—3-foot tourist line 1970–2014. Anaka, Myrtle, 2023 and 2025 fires, September 2026 scrapping. Roster, Hahakea trestle, Pioneer Mill corridor.
-
Massachusetts Christmas Train Rides (2026): A Complete Guide
Sep 09, 26 08:16 AM
 2026 Massachusetts Christmas trains—Shelburne Falls Moonlight Magic Friday Nov. 27; Edaville Festival of Lights in Carver. Polar is Cape Cod Central in Buzzards Bay.